Showing 1–20 of 436
-
Carbon Flows Update 2026 – Compilation of Supply and Demand of Fossil and Renewable Carbon for Chemicals and Derived Materials on a Global and European Level
Markets & Economy, Policy, Sustainability & Health, Technology
81 Pages
331 Downloads
331 Downloads
2026-10
FREE
Free Shipping331
DownloadsThree years after the first Carbon Flow Report in 2023, the update incorporates new data and a significantly improved methodology. Scientists at nova-Institute have developed a new system approach to trace carbon flows from feedstocks to products along the chemical value chain. Covering more than 40 chemical value chains, this approach provides a reliable dataset on embedded carbon flows while systematically excluding double counting.
In 2023, global demand for carbon feedstock in chemicals and derived materials amounted to 660 million tonnes of carbon per year, with 86% originating from fossil resources, 10% from biomass and 4% from recycling. Including all carbon based materials, total demand reached 1,400 million tonnes of carbon per year, with biomass and recycled biomass contributing 46%. In the EU, carbon feedstock demand amounted to 85 million tonnes of carbon per year, representing 13% of global demand. The European feedstock mix differs from the global average, with a biomass share of approximately 8% and a higher recycling share of 9%. The updated figures reflect methodological improvements and developments in the European chemical and recycling sectors. The report also presents an updated exploratory scenario for a global chemical industry with net zero emissions by 2050. It assumes an annual growth rate of 2%, a recycling share of 50% and a biomass contribution of 20 to 30%. The scenario is not a prediction, as its realisation depends on political framework conditions and investments.
Based on scientific literature, statistical databases, industry data and expert consultation, the report contains more than 30 graphics and tables with descriptions of methodology, sources and data. It is designed as a living document that will be updated regularly.
Feedback, additional input and new data are welcome. Please contact Christopher vom Berg, Head of the Renewable Feedstock Department at nova-Institut, at christopher.vomberg@nova-institut.de.
DOI: 10.5258/BCXC5064
-
Biomass Utilisation by the Global and EU Chemical Industry (2023 & 2024)
Markets & Economy
28 Pages
136 Downloads 136 Downloads
2026-10
FREE
Free Shipping136
DownloadsThe volume of biomass utilised by the global and European chemical industries is almost unknown. There are no official statistics available, so everyone relies on rough estimates. Scientists at nova-Institute have collected and pieced together hundreds of puzzle pieces to develop the best global estimate available. Originally developed for the RCI/BIC Biomass Potential Study, this document has now been updated as part of the RCI Carbon Flows Study Update 2026.
The update provides an improved baseline of current global and European biomass demand, with a particular focus on feedstock demand in the chemical industry. The analysis draws on sources published mainly in 2024–2026, with underlying market and production data primarily referring to 2023 and 2024. Where necessary, earlier proxy data or more recent estimates are used. The analysis is based on extensive data research, expert interviews, and input from the relevant Project Advisory Board, as well as other stakeholders and industry experts. The sources and our calculation pathway are clearly shown. The allocation of biomass to the chemical industry depends strongly on system boundaries and definitions. In this study, biomass use is consistently allocated at the level of feedstock demand rather than downstream products. As intermediate products such as ethanol may be reported either as final products or as precursors to downstream chemicals (e.g. ethylene or polymers), inconsistencies across datasets can lead to double counting. To address this, biomass is accounted for only once at the feedstock level, and downstream products derived from these intermediates are not counted separately.
Please use our data for your market analysis and future strategies. If you have access to better data on certain biomass types or application sectors, we would be grateful if you could share it with us. This is intended to be a living document and will be updated regularly. Please contact: michael.carus@nova-institut.de
-
Toward a Defossilized Chemical Industry – Trends in Europe (Affiliate product) (PDF)
Markets & Economy, Sustainability & Health, Technology
37 Pages
2026-08
FREE
Free Shipping0
More
Downloads
infoChemicals are present in more than 90% of manufactured goods, and almost everything from solar panels to pharmaceuticals is made with the help of chemicals. It is still largely based on fossil raw materials and is a major consumer of fossil resources and energy. Because Europe is committed to reducing CO2 emissions from fossil sources in the interest of climate protection, the chemical industry must reduce its fossil fuel footprint. Key measures for achieving this goal are the decarbonization of energy and the defossilization of carbon embedded in chemical products.
In this brief, we discuss the status and future trends of renewable energy supplies in Europe, including hydrogen, and the status and trends of the development of green carbon chemicals through recycling, bioproduction in biorefineries, and the use of CO2 as feedstock (CCU, carbon capture and utilization). We also refer to the current approaches to climate neutrality of major chemical producers in Europe.
Direct download via the renewable-carbon.eu/publications is not possible.
Please follow this link: https://doi.org/10.1016/j.greenca.2026.01.007 -
Why is Vioneo building its first methanol-to-PP/PE plant in China rather than Europe?
Markets & Economy, Policy
3 Pages
64 Downloads 64 Downloads
2026-05
FREE
Free Shipping64
DownloadsZOOM-Interview with Alex Hogan (CEO of Vioneo) by Michael Carus (nova-Institut/RCI), 11 May 2026
The vision of Vioneo as ‘fossil-free pioneers for the plastics industry, using green methanol to produce fossil-free polypropylene and polyethylene on a commercial scale‘ will be realised in China, not in Europe. Michael asks Alex why this is the case.
Mandatory EU legislation (quotas, definitions, regulatory differentiation) is the single most important enabler for Vioneo — and similar companies — to invest in Europe. Without it, the market remains voluntary, price-driven, and commercially unviable for premium fossil-free products.
As Europe is a more expensive production location than the US or Asia, the only way forward – as Alex Hogan makes clear – is to create clear, strong and lasting framework conditions in Europe to generate robust demand for renewable chemistry and plastics, as well as to build the infrastructure that makes production in the EU possible. These framework conditions are indeed being discussed and are planned, but it is not certain whether they will actually materialise, in what form, or when. But who invests in hopes and announcements?
-
Could the production of European chemicals be achieved without naphtha and steam crackers? What alternative pathways could be viable in the future? (PDF)
Markets & Economy, Policy, Technology
7 Pages
160 Downloads 160 Downloads
2026-05
FREE
Free Shipping160
DownloadsOver the next few decades, naphtha steam cracking will remain the dominant and most efficient process in the European chemical industry. However, naphtha is produced from crude oil, which is linked to several problems: (1) climate change, especially from Scope 3 emissions; (2) a linear instead of a circular economy; (3) most innovation taking place in other areas than crackers; (4) a failure to achieve resilience and strategic autonomy; and (5) Europe’s inability to compete with other regions of the world that have better access to cheaper crude oil and naphtha. Furthermore, (6) renewable naphtha produced from biomass, waste or CO₂ is very expensive (2–3 times more expensive), and (7) other pathways than naphtha and steam crackers are often more efficient for these alternative renewable feedstocks.
These are seven good reasons to discuss what alternative pathways could be viable in the future of Europe’s chemical industry and how they could be implemented. This paper mainly focuses on methanol, ethanol and biodiesel. Before delving into these topics, two brief comments on ammonia production, biotechnology and biomanufacturing and electrochemistry are provided.
-
Investments totalling more than 5 billion with a future bio-based quota for plastics in Europe (PDF)
Markets & Economy, Policy
3 Pages
104 Downloads 104 Downloads
2026-05
FREE
Free Shipping104
DownloadsImplementing a 5% bio-based quota for all polymers produced in Europe could be just as successful as the introduction of biofuels.
As a draft scenario, we assume that (1) 30% will come from bio-attributed sources, (2) 25% from dedicated bio-based polymers, and (3) 45% from drop-in bio-based polymers. What would this require in terms of investment? Based on these assumptions, a 5% bio-based (including bio-attributed) polymer quota would generate €5.3 billion in investment, similar to the level of investment in first-generation biofuels. A subsequent 30% bio-based (including bio-attributed) polymer quota would generate €32 billion, similar to the level of investment in sustainable aviation fuels (SAF) in the next decades.
-
CO2-based Fuels and Chemicals Conference 2026 (Proceedings, PDF)
Markets & Economy, Policy, Sustainability & Health, Technology
2026-05
150 € ex. tax
Plus 19% MwSt.Press
release Add to
cartThe proceedings of the CO2-based Fuels and Chemicals Conference 2026 (28-29 April 2026, https://co2-chemistry.eu) contain all released presentations (download of the program leaflet, PDF) and the press release of the three winners of the Innovation Award “Best CO2 Utilisation 2026″.
-
Support for bio-based feedstock in plastic packaging analysis under the Packaging and Packaging Waste Regulation (EU) 2025/40 (Affiliate product)
Markets & Economy, Policy, Sustainability & Health, Technology
100 Pages
2026-05
FREE
Free Shipping0
More
Downloads
infoNew publication from nova experts for the European Commission
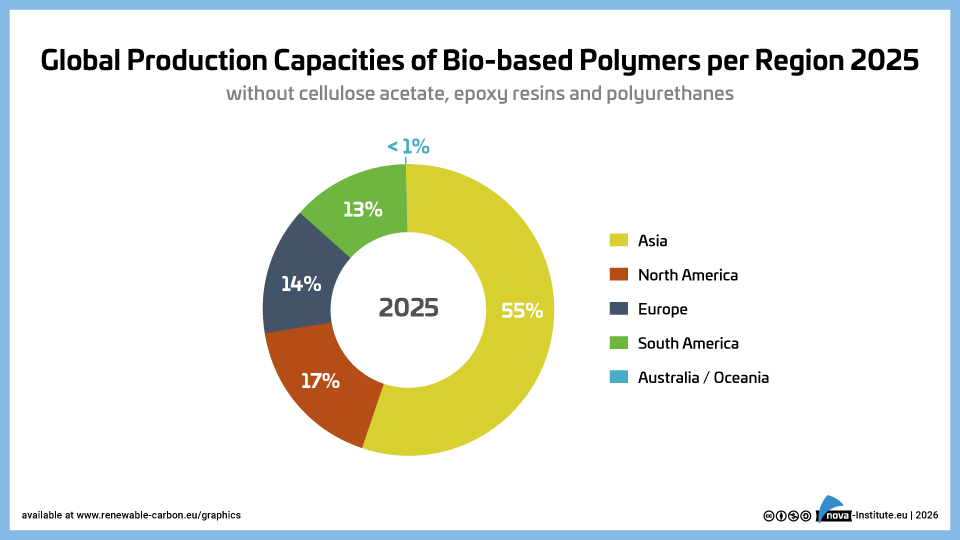
This report assesses the role of bio-based feedstocks in plastic packaging under the EU’s Packaging and Packaging Waste Regulation (PPWR), with a focus on technological development and environmental performance. Although seventeen bio-based polymers are commercially available, they represent only ~1% of the global plastics market and account for just 4–5% of biogenic carbon in the EU chemical sector. Production capacity is concentrated in Asia (55%), followed by North America (17%) and the EU27+3 (14%). Despite their limited market share, there are no fundamental technical barriers to using them in packaging. Bio-based plastics offer a 30–70% reduction in greenhouse gas emissions compared to fossil-based alternatives, which supports the EU’s decarbonisation and circular economy goals. The report also evaluates the feasibility of setting targets for the use of bio-based materials, their equivalence with recycled materials and how sustainability criteria can be aligned with the Renewable Energy Directive (RED). Key recommendations include setting binding targets for bio-based content, establishing harmonised sustainability criteria, and adapting recycling infrastructure. Leveraging the complementarity of bio -based and recycled content could help to accelerate the EU’s transition to a climate-neutral packaging sector.Direct download via the renewable-carbon.eu/publications is not possible. -
AI Circular Economy Conference 2026 (Proceedings, PDF)
Markets & Economy, Policy, Sustainability & Health, Technology
2026-03
150 € ex. tax
Plus 19% MwSt.Press
release Add to
cartThe proceedings of the AI Circular Economy Conference 2026 (4-5 March, https://ai-circulareconomy.eu ) contain 25 conference presentations and the press release. Download of the program leaflet.
-
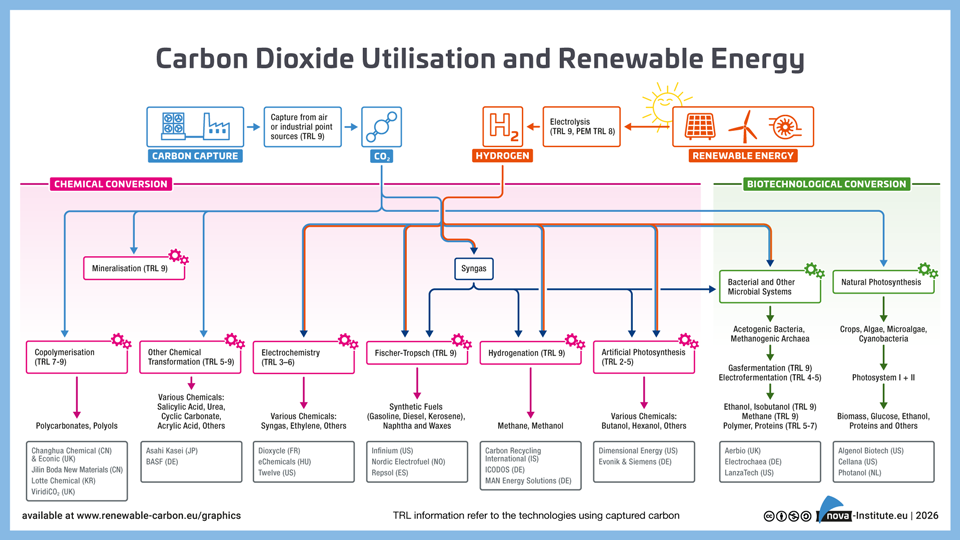
Carbon Dioxide Utilisation and Renewable Energy − Graphic (PNG)
Markets & Economy, Technology
1 Page
120 Downloads 120 Downloads
2026-02
FREE
Free Shipping120
Downloads -
84 Downloads
2026-02
FREE
Free Shipping84
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
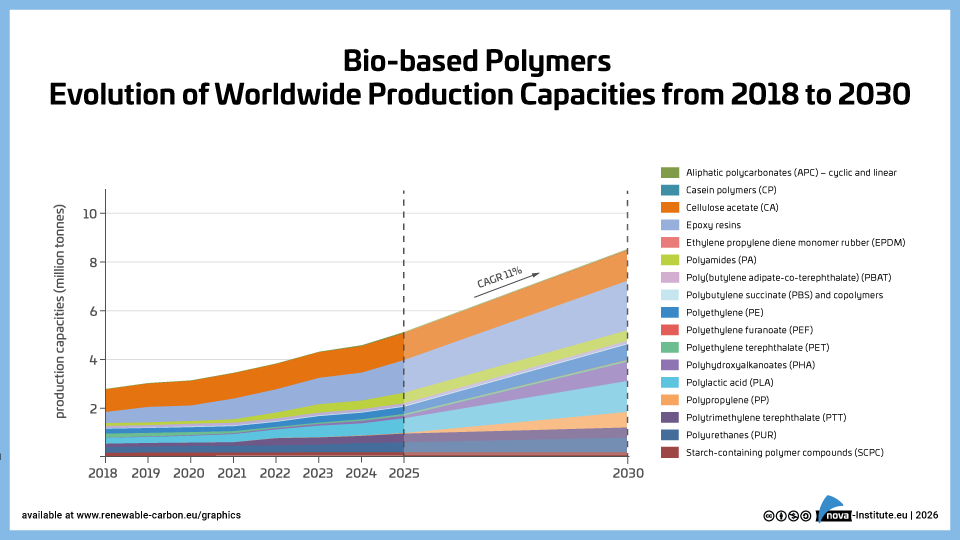
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
60 Downloads
2026-02
FREE
Free Shipping60
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
Bio-based polymers – Evolution of worldwide production capacities from 2018 to 2030 (PNG)
Markets & Economy
1 Page
77 Downloads 77 Downloads
2026-02
FREE
Free Shipping77
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
Global Production Capacities of Bio-based Polymers per region 2025 (PNG)
Markets & Economy
1 Page
46 Downloads 46 Downloads
2026-02
FREE
Free Shipping46
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
Bio-based non biodegradable polymers Evolution of Capacities (PNG)
Markets & Economy
1 Page
32 Downloads 32 Downloads
2026-02
FREE
Free Shipping32
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
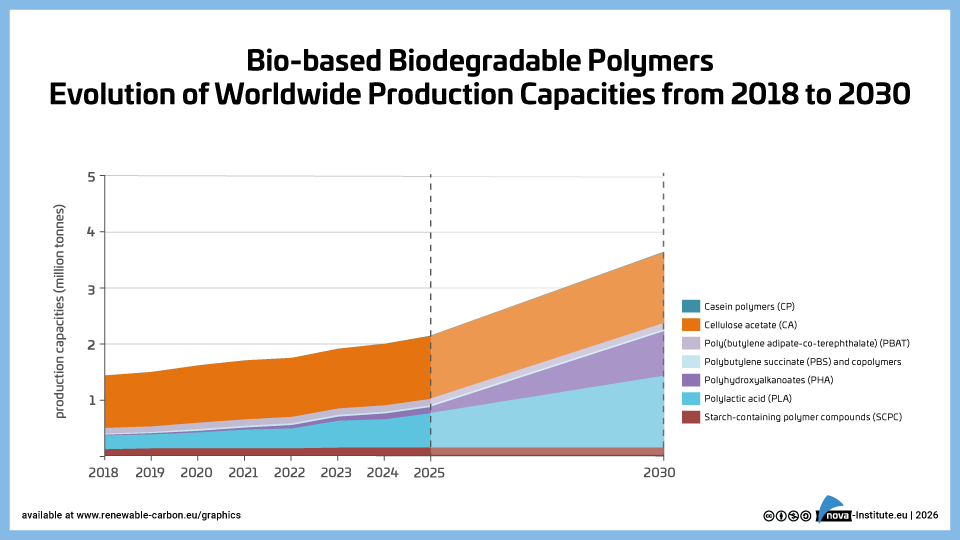
Bio-based biodegradable polymers-Evolution Capacities to 2030 (PNG)
Markets & Economy
1 Page
53 Downloads 53 Downloads
2026-02
FREE
Free Shipping53
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
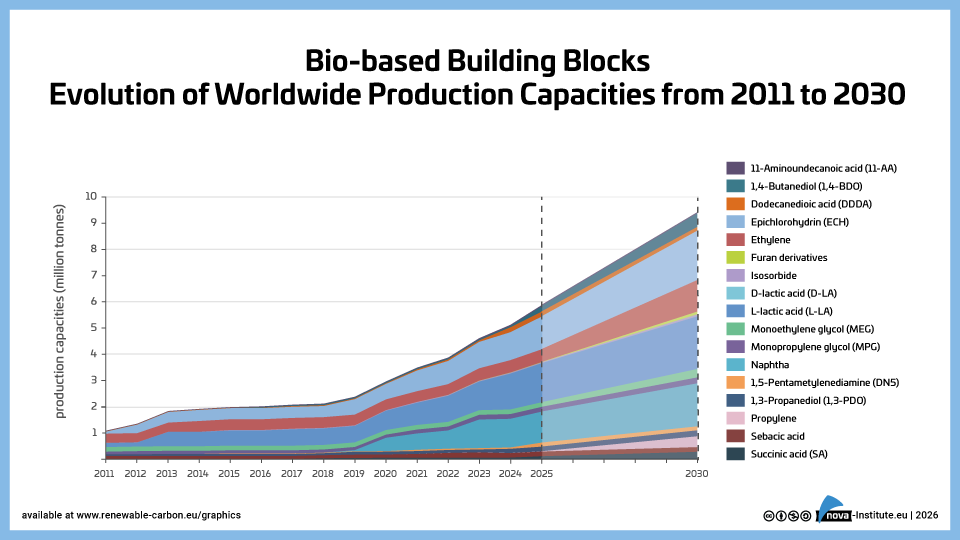
Bio-based building blocks – Evolution of capacities to 2030 (PNG)
Markets & Economy
1 Page
41 Downloads 41 Downloads
2026-02
FREE
Free Shipping41
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
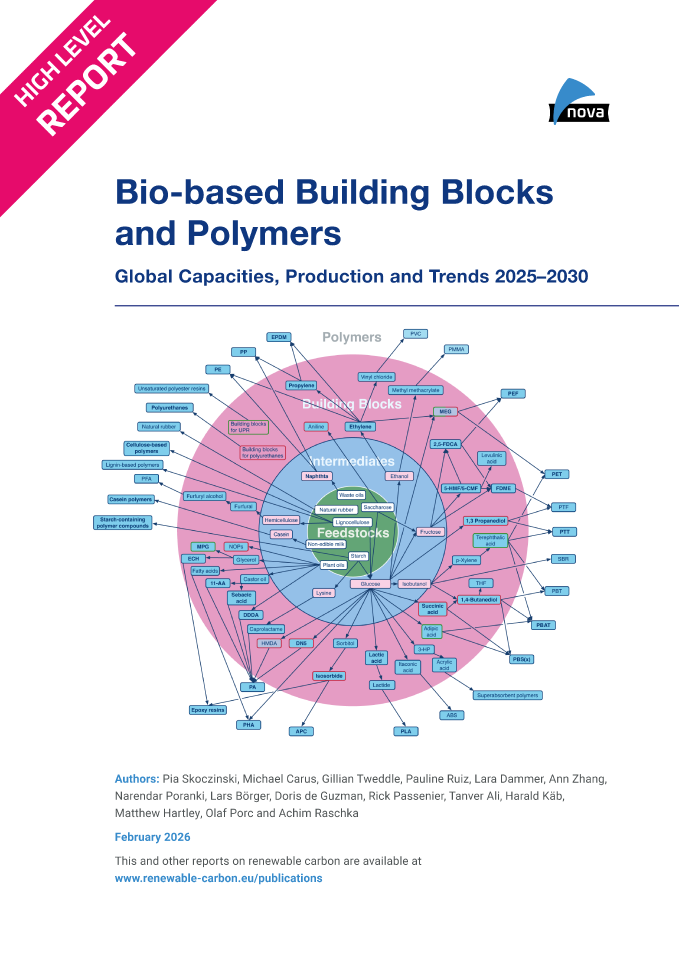
Bio-based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030 (PDF)
Markets & Economy
23 Pages
1608 Downloads 1608 Downloads
2026-02
FREE
Free Shipping1608
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
142 Downloads
2026-02
FREE
Free Shipping142
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
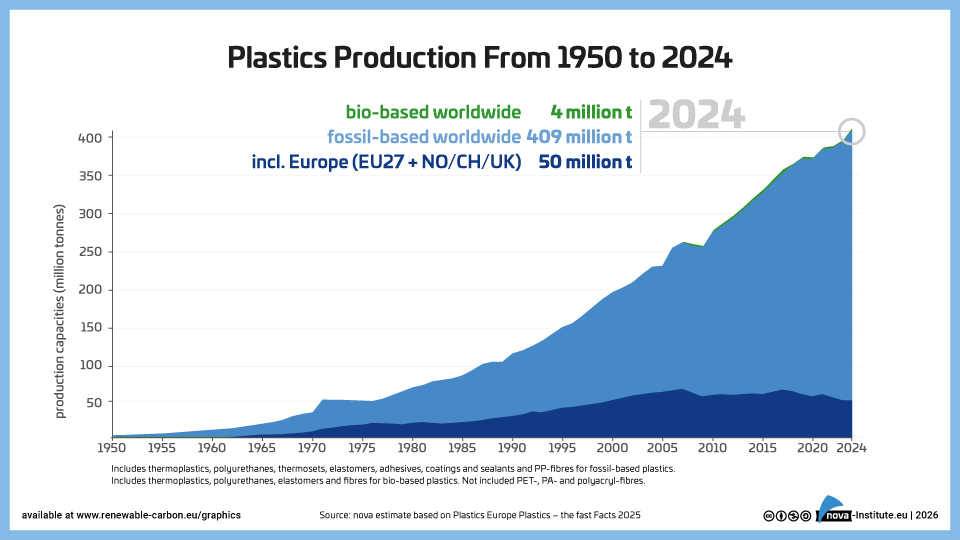
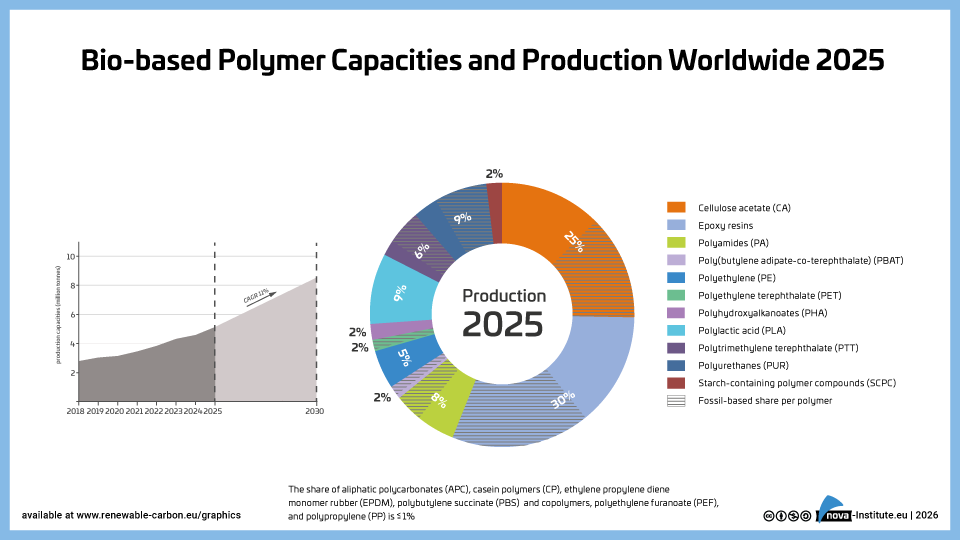
Bio-based Polymer Capacities and Production Worldwide 2025 (PNG)
Markets & Economy
1 Page
64 Downloads 64 Downloads
2026-02
FREE
Free Shipping64
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285