
Showing 1–20 of 83
-
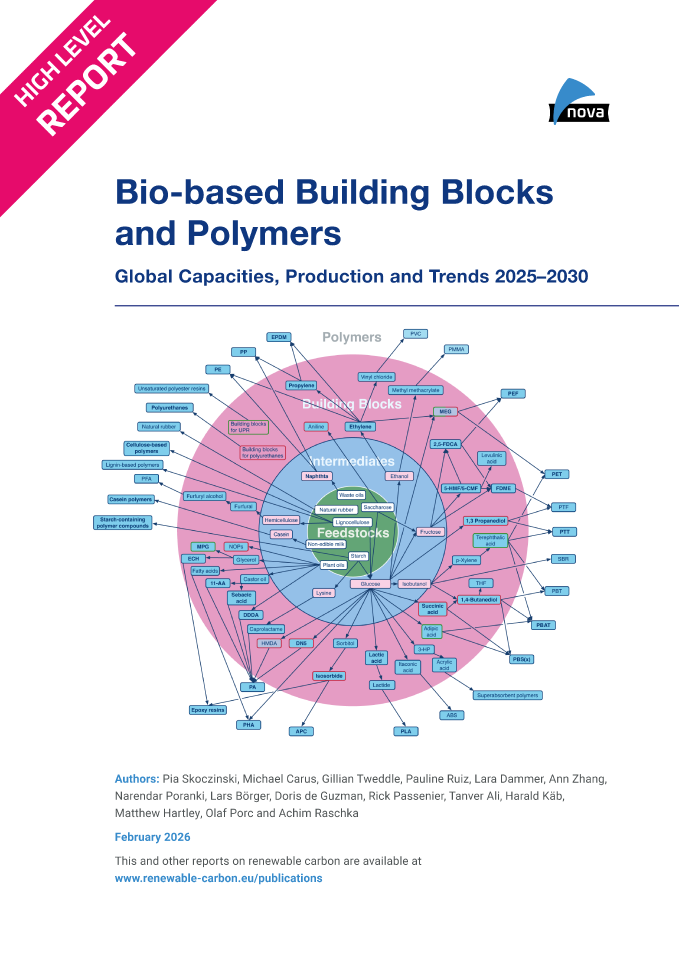
Bio-based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030 (PDF)
NewMarkets & Economy
23 Pages
1500 Downloads
1500 Downloads
2026-02
FREE
Free Shipping1500
DownloadsThe new high-level report “Bio‑based Building Blocks and Polymers – Global Capacities, Production and Trends 2025–2030”, compiled by the international biopolymer expert group of the nova-Institute, provides an overview of the capacities and production data of 17 commercially available bio‑based building blocks and polymers in 2025, along with a forecast for 2030. Detailed market data is available via individual workshops and webinars with the biopolymer experts. This data includes capacity development from 2018 to 2030, production data for the years 2024 and 2025, and analyses of market developments per building block, polymer and producers, as well as a statistical analysis of “Mass Balance and Attribution (MBA)” products available worldwide.
2025 was a solid year for bio-based polymers, with an expected overall CAGR of 11 % to 2030 and an average capacity utilisation rate of 86 %. Overall, bio-based non-biodegradable polymers have larger installed capacities and higher utilisation rates than bio-based biodegradable polymers. While 58 % of the total installed capacities are from bio-based non-biodegradable polymers, 42 % are bio-based biodegradable polymers. Bio-based non-biodegradable have an average utilisation rate of 90 % whereas bio-based biodegradable polymers have an average utilisation rate of 81 %. The expected CAGR for both, bio-based non-biodegradable and biodegradable is similar with 10 % and 11 %, respectively.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PE and PP are increasing by 17 % and 94 %. Also, capacities for the biodegradables PHA and PLA are expected to increase until 2030 by 49 % and 16 %, respectively. Commercial newcomers such as casein polymers and PEF have increased production capacity and are expected to continue to grow significantly until 2030.
DOI No.: https://doi.org/10.52548/PILO4285
-
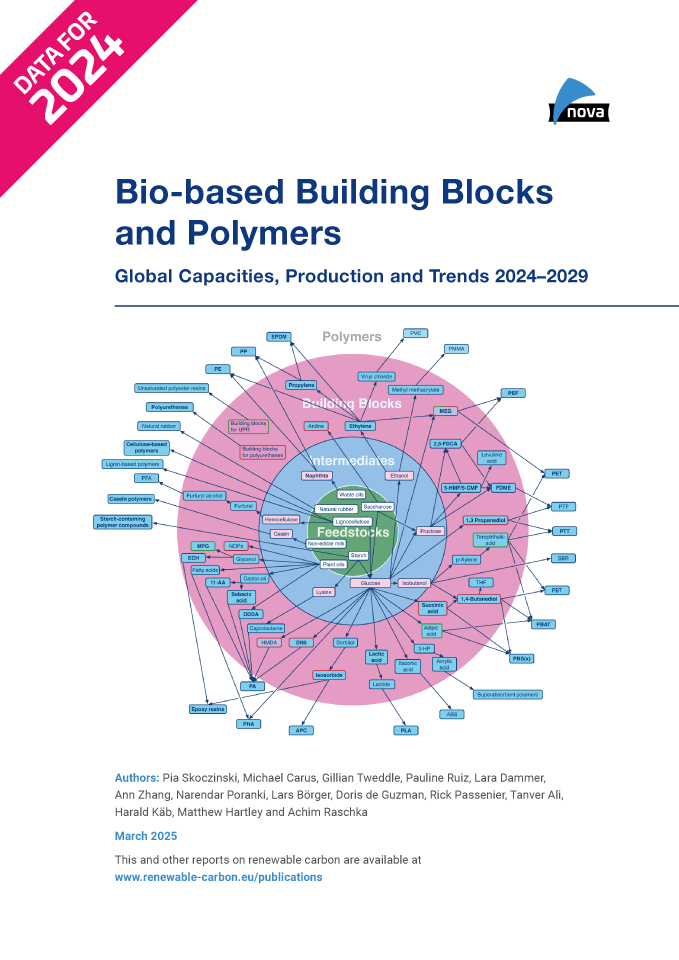
Bio-based Building Blocks and Polymers – Global Capacities, Production and Trends 2024–2029 (PDF)
NewMarkets & Economy
434 Pages
2025-03
3,000 € – 10,000 €Price range: 3,000 € through 10,000 € ex. tax
Plus 19% MwSt.Press
release Select
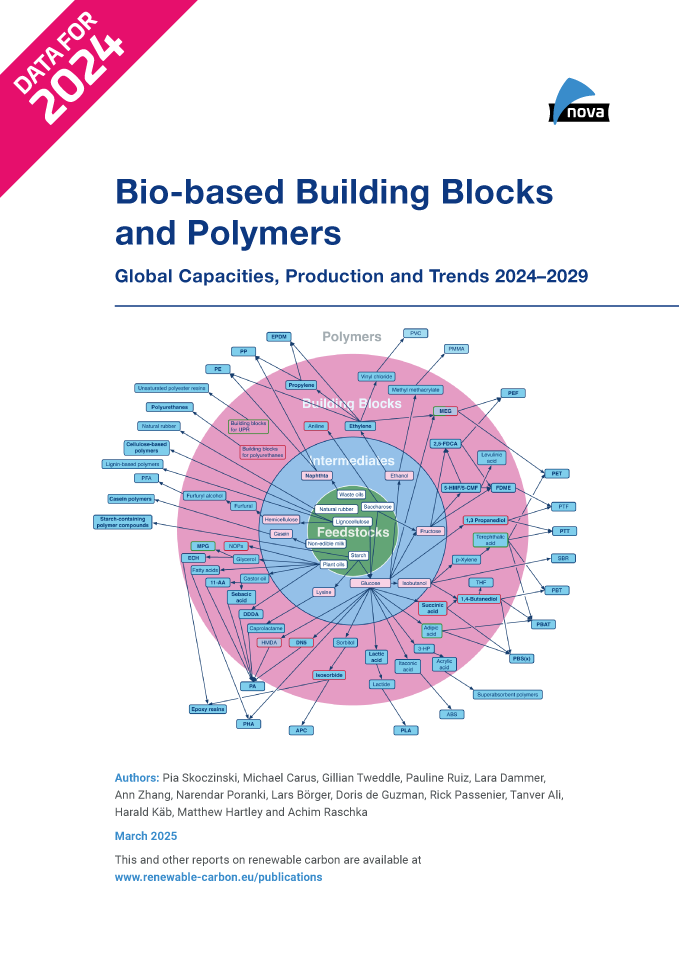
licence2024 was a respectable year for bio-based polymers, with an overall expected CAGR of 13 % to 2029. Overall, bio-based biodegradable polymers have large installed capacities with an expected CAGR of 17 % to 2029, but the current average capacity utilisation is moderate at 65 %. In contrast, bio-based non-biodegradable polymers have a much higher utilisation rate of 90 %, but will only grow by 10 % to 2029.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PP and cyclic APC capacities are increasing by 30 %. Despite a decline in production of biodegradables, especially for PLA in Asia, capacities have increased by 40 %. The same applies to PHA capacities. Commercial newcomers such as casein polymers and PEF recorded a rise in production capacity and are expected to continue to grow significantly until 2029.
DOI No.: https://doi.org/10.52548/UMTR4695
-
Investments totalling more than 5 billion with a future bio-based quota for plastics in Europe (PDF)
Markets & Economy, Policy
3 Pages
98 Downloads 98 Downloads
2026-05
FREE
Free Shipping98
DownloadsImplementing a 5% bio-based quota for all polymers produced in Europe could be just as successful as the introduction of biofuels.
As a draft scenario, we assume that (1) 30% will come from bio-attributed sources, (2) 25% from dedicated bio-based polymers, and (3) 45% from drop-in bio-based polymers. What would this require in terms of investment? Based on these assumptions, a 5% bio-based (including bio-attributed) polymer quota would generate €5.3 billion in investment, similar to the level of investment in first-generation biofuels. A subsequent 30% bio-based (including bio-attributed) polymer quota would generate €32 billion, similar to the level of investment in sustainable aviation fuels (SAF) in the next decades.
-
Support for bio-based feedstock in plastic packaging analysis under the Packaging and Packaging Waste Regulation (EU) 2025/40 (Affiliate product)
Markets & Economy, Policy, Sustainability & Health, Technology
100 Pages
2026-05
FREE
Free Shipping0
More
Downloads
infoNew publication from nova experts for the European Commission
This report assesses the role of bio-based feedstocks in plastic packaging under the EU’s Packaging and Packaging Waste Regulation (PPWR), with a focus on technological development and environmental performance. Although seventeen bio-based polymers are commercially available, they represent only ~1% of the global plastics market and account for just 4–5% of biogenic carbon in the EU chemical sector. Production capacity is concentrated in Asia (55%), followed by North America (17%) and the EU27+3 (14%). Despite their limited market share, there are no fundamental technical barriers to using them in packaging. Bio-based plastics offer a 30–70% reduction in greenhouse gas emissions compared to fossil-based alternatives, which supports the EU’s decarbonisation and circular economy goals. The report also evaluates the feasibility of setting targets for the use of bio-based materials, their equivalence with recycled materials and how sustainability criteria can be aligned with the Renewable Energy Directive (RED). Key recommendations include setting binding targets for bio-based content, establishing harmonised sustainability criteria, and adapting recycling infrastructure. Leveraging the complementarity of bio -based and recycled content could help to accelerate the EU’s transition to a climate-neutral packaging sector.Direct download via the renewable-carbon.eu/publications is not possible. -
2025-12
FREE
Free Shipping2
More
Downloads
infoThe fashion industry is under growing pressure to shift towards more sustainable production methods and materials. Traditional petroleum-based materials dominate the textile and footwear industry. There is increasing interest in exploring alternative, more sustainable feedstocks, such as bio-based materials derived from carbon capture technologies. These alternatives offer potential environmental benefits but require thorough analysis to understand the technical feasibility, environmental impact, and regulatory considerations involved.
The nova-Institute (hereafter referred to as nova) was engaged by Fashion for Good and some of its partners to conduct an in-depth assessment of sustainable feedstocks and conversion technologies for producing polymers, specifically focusing on bio-(PET, PA, EVA and BDO). The aim was to create a comprehensive understanding of the technological routes available for using bio-based feedstocks and emerging CO2 conversion technologies in the production of polymers used in the textile industry. Additionally, nova assessed sustainability standards and certification schemes to ensure the feedstocks meet stringent environmental and social criteria.
Direct download via the renewable-carbon.eu/publications is not possible.
Please follow this link:
https://www.fashionforgood.com/case-study/biosynthetic-feedstock -
2025-08
500 € – 1,000 €Price range: 500 € through 1,000 € ex. tax
Plus 19% MwSt.Press
release Select
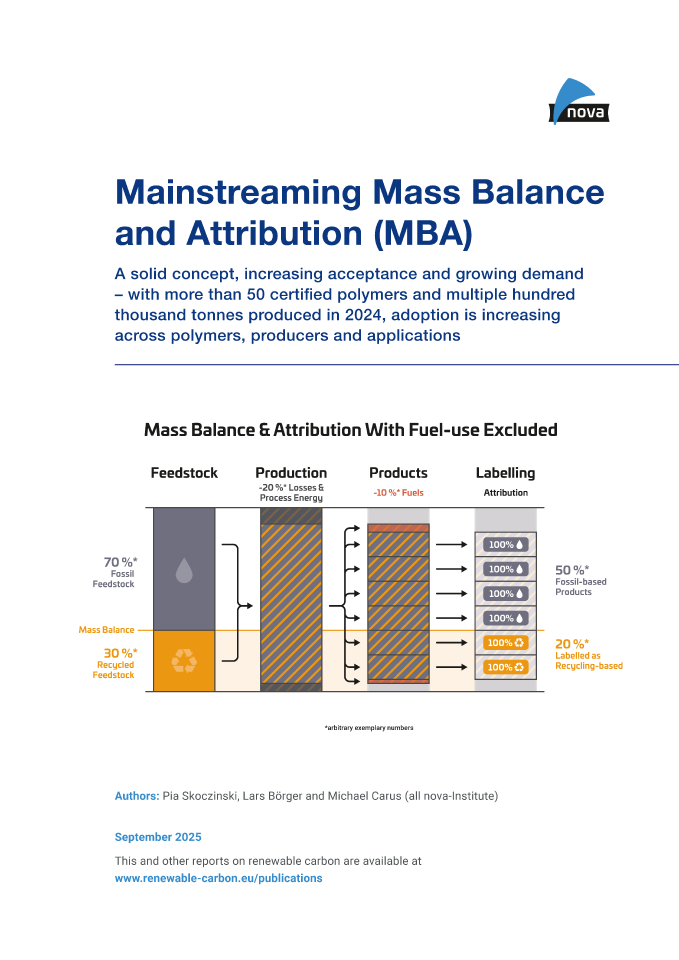
licenceA solid concept, increasing acceptance and growing demand – with more than 50 certified polymers and multiple hundred thousands of kilotonnes produced in 2024, adoption is increasing across polymers, producers and applications
The acceptance and accessibility of mass balanced attributed (MBA) chemicals, building blocks and polymers is a major issue for the chemical and plastics sectors, as well as for brand owners. MBA products could provide more options, better availability and reduced costs for the defossilisation compared to dedicated bio-based solutions.
However, both the MBA concept and the political regulations are crucial for scaling up, but difficult to understand. Furthermore, discussions about potentially misleading communication on the concept are confusing stakeholders. In addition, no production volumes are available.The new report “Mainstreaming Mass Balance and Attribution (MBA): A solid concept, increasing acceptance and growing demand – with more than 50 certified polymers and multiple hundred thousand tonnes produced in 2024, adoption is increasing across polymers, producers and applications” highlights this evolving landscape.
The first part of the report covers terminology, the historical development, the rationale and acceptance, and the latest regulatory environment in Brussels. The second part is dedicated to the underlying data.It covers feedstock used for certified MBA products, as well as the most frequently produced MBA chemicals and polymers (PE is No. 1). The leading producers (BASF is No. 1) and regions are identified, with 60 % of demand from Europe, and the largest share stemming from Germany, Belgium and France.
DOI No.: https://doi.org/10.52548/VDRG6920
-
Bio-based Building Blocks and Polymers Global Capacities, Production and Trends 2024–2029 – Short Version (PDF)
Markets & Economy
28 Pages
1642 Downloads 1642 Downloads
2025-03
FREE
Free Shipping1642
Downloads2024 was a respectable year for bio-based polymers, with an overall expected CAGR of 13 % to 2029. Overall, bio-based biodegradable polymers have large installed capacities with an expected CAGR of 17 % to 2029, but the current average capacity utilisation is moderate at 65 %. In contrast, bio-based non-biodegradable polymers have a much higher utilisation rate of 90 %, but will only grow by 10 % to 2029.
Epoxy resin and PUR production is growing moderately at 9 and 8 %, respectively, while PP and cyclic APC capacities are increasing by 30 %. Despite a decline in production of biodegradables, especially for PLA in Asia, capacities have increased by 40 %. The same applies to PHA capacities. Commercial newcomers such as casein polymers and PEF recorded a rise in production capacity and are expected to continue to grow significantly until 2029.
-
Bio-based Polymers Worldwide (PDF)
Markets & Economy, Policy, Sustainability & Health
5 Pages
902 Downloads 902 Downloads
2025-02
FREE
Free Shipping902
DownloadsExpert insight into capacity developments, investments and new policy frameworks:- Firstly, global capacity for bio-based polymers will grow strongly over the next five years, much faster than for fossil-based polymers
- Secondly, investments in new capacity will take place in China, Europe, the Middle East, and the US
- Thirdly, investment in bio-based polymer capacities is mainly driven by policy frameworks that create demand.
-
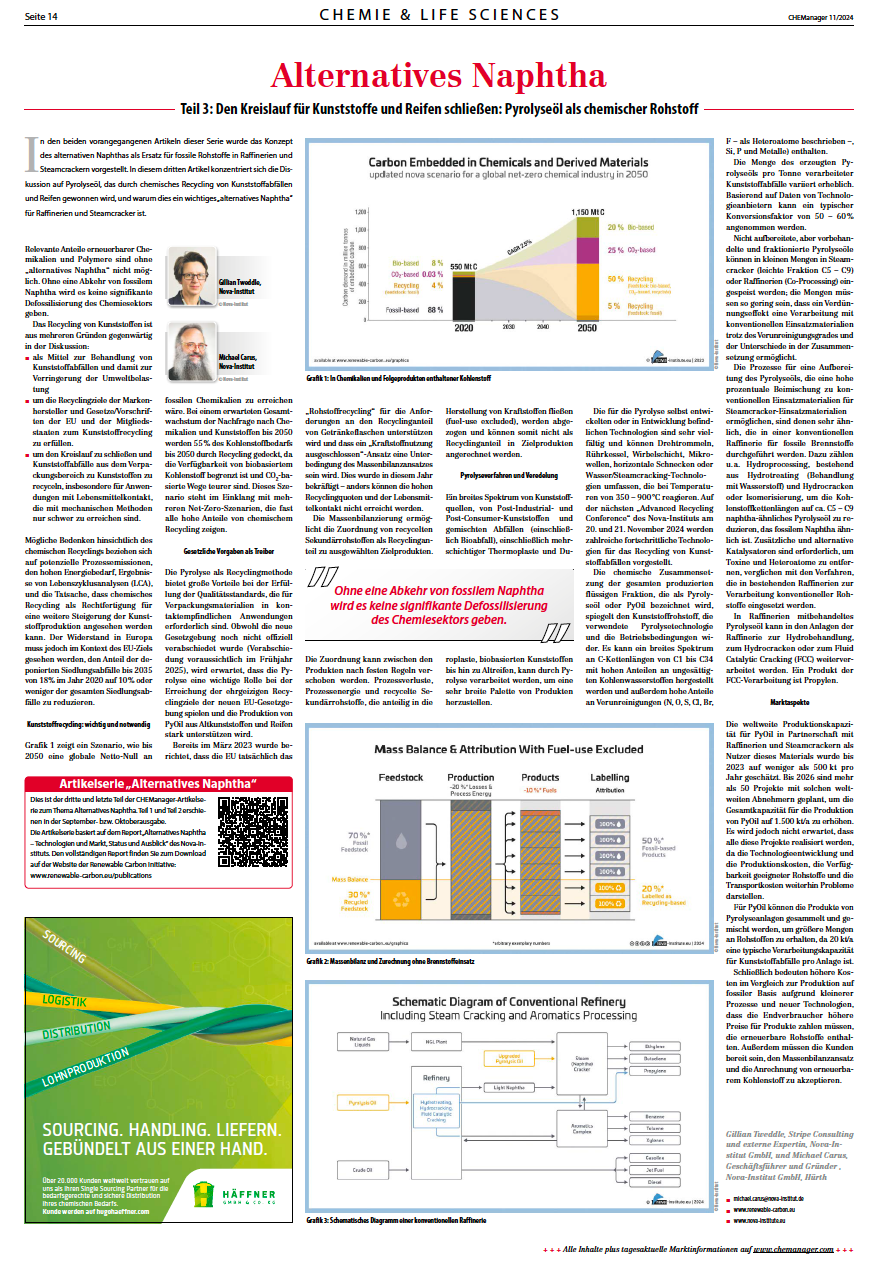
Alternatives Naphtha – Den Kreislauf für Kunststoffe und Reifen schließen: Pyrolyseöl als chemischer Rohstoff (Gastbeitrag Teil 3) (PDF)
Markets & Economy, Technology
1 Page
118 Downloads
118 Downloads
2024-11
FREE
118
DownloadsIn den beiden vorangegangenen Artikeln dieser Serie wurde das Konzept des alternativen Naphthas als Ersatz für fossile Rohstoffe in Raffinerien und Steamcrackern vorgestellt. In diesem dritten Artikel konzentriert sich die Diskussion auf Pyrolyseöl, das durch chemisches Recycling von Kunststoffabfällen und Reifen gewonnen wird, und warum dies ein wichtiges „alternatives Naphtha“ für Raffinerien und Steamcracker ist.
Relevante Anteile erneuerbarer Chemikalien und Polymere sind ohne „alternatives Naphtha“ nicht möglich. Ohne eine Abkehr von fossilem Naphtha wird es keine signifikante Defossilisierung des Chemiesektors geben.
Dieser Artikel ist im Rahmen einer Serie von Gastbeiträgen im CHEManager erschienen. Es handelt sich um „Alternatives Naphtha Teil 3“ – aus CHEManager 11/2024.
Hier finden sie den Artikel auch bei CHEManager.
-
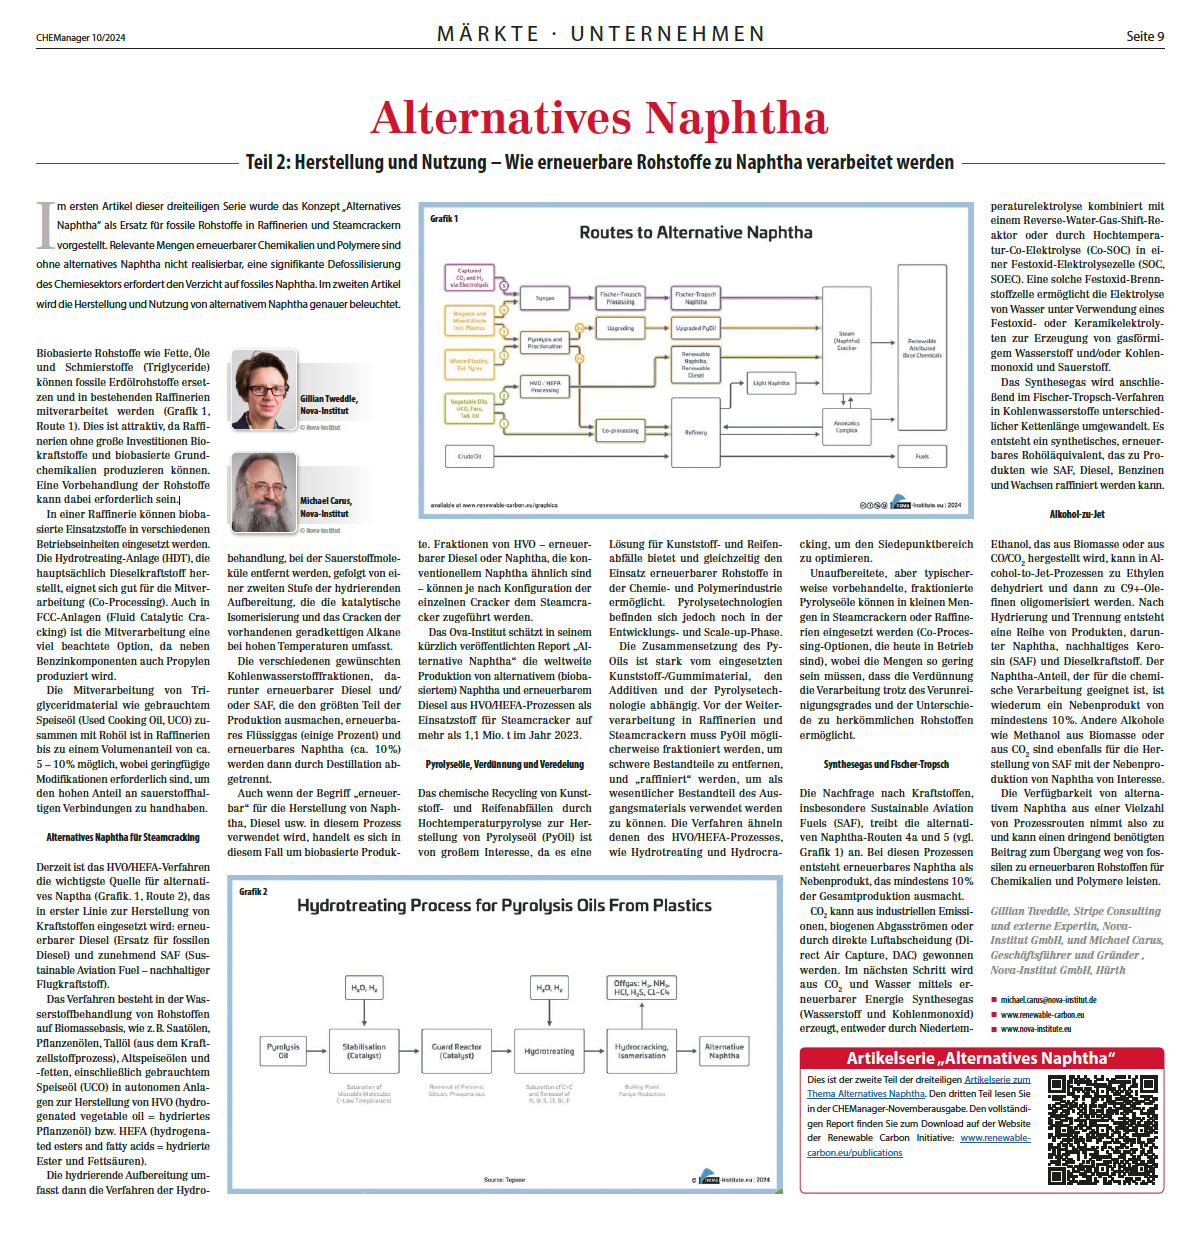
Alternatives Naphtha – Herstellung und Nutzung – Wie erneuerbare Rohstoffe zu Naphtha verarbeitet werden (Gastbeitrag Teil 2) (PDF)
Markets & Economy, Technology
1 Page
69 Downloads 69 Downloads
2024-10
FREE
69
DownloadsIm ersten Artikel dieser dreiteiligen Serie wurde das Konzept „Alternatives Naphtha“ als Ersatz für fossile Rohstoffe in Raffinerien und Steamcrackern vorgestellt. Relevante Mengen erneuerbarer Chemikalien und Polymere sind ohne alternatives Naphtha nicht realisierbar, eine signifikante Defossilisierung des Chemiesektors erfordert den Verzicht auf fossiles Naphtha. Im zweiten Artikel wird die Herstellung und Nutzung von alternativem Naphtha genauer beleuchtet.
Biobasierte Rohstoffe wie Fette, Öle und Schmierstoffe (Triglyceride) können fossile Erdölrohstoffe ersetzen und in bestehenden Raffinerien mitverarbeitet werden. Dies ist attraktiv, da Raffinerien ohne große Investitionen Biokraftstoffe und biobasierte Grundchemikalien produzieren können. Eine Vorbehandlung der Rohstoffe kann dabei erforderlich sein.
Dieser Artikel ist im Rahmen einer Serie von Gastbeiträgen im CHEManager erschienen. Es handelt sich um „Alternatives Naphtha Teil 2“ – aus CHEManager 10/2024.
-
nova-paper #17: Science-based Definition of Natural Polymers (PDF)
Markets & Economy, Policy, Sustainability & Health
22 Pages
788 Downloads 788 Downloads
2024-09
FREE
Free Shipping788
DownloadsEuropean policy has defined „natural polymers“ in a way that has caused much concern and debate among scientists and industry, and has created a barrier to innovation. The authors of this report have carried out a comprehensive scientific evaluation of how the scientific literature defines „natural polymers“, and the result is: The European policy definition is partly in clear contrast to the scientific definitions.
„Occurring in nature“ is the basis for every definition of „natural polymers“ in the scientific literature and in policy. All scientific definitions include biotechnological processes for the production of natural polymers. Not a single definition mentions the place of polymerisation as a criterion – in clear contrast to European policy. Industrial practice confirms this finding: A long list of widely accepted natural polymers includes biotechnologically processed polymers and the place of polymerisation is not a criterion.
Conclusion: A policy definition of „natural polymers“ that is at odds with almost all scientific definitions and at odds with business reality, and which is a major barrier to innovation, green investment and lower carbon footprints, needs to be revised.
The essence of the scientific definitions evaluated in this report is simple and leads to the following proposed definition: „Natural polymers are those that occur in nature, are produced in and extracted from nature, or can be produced identically using biotechnological processes“.DOI No.: https://doi.org/10.52548/UGBZ5516
-
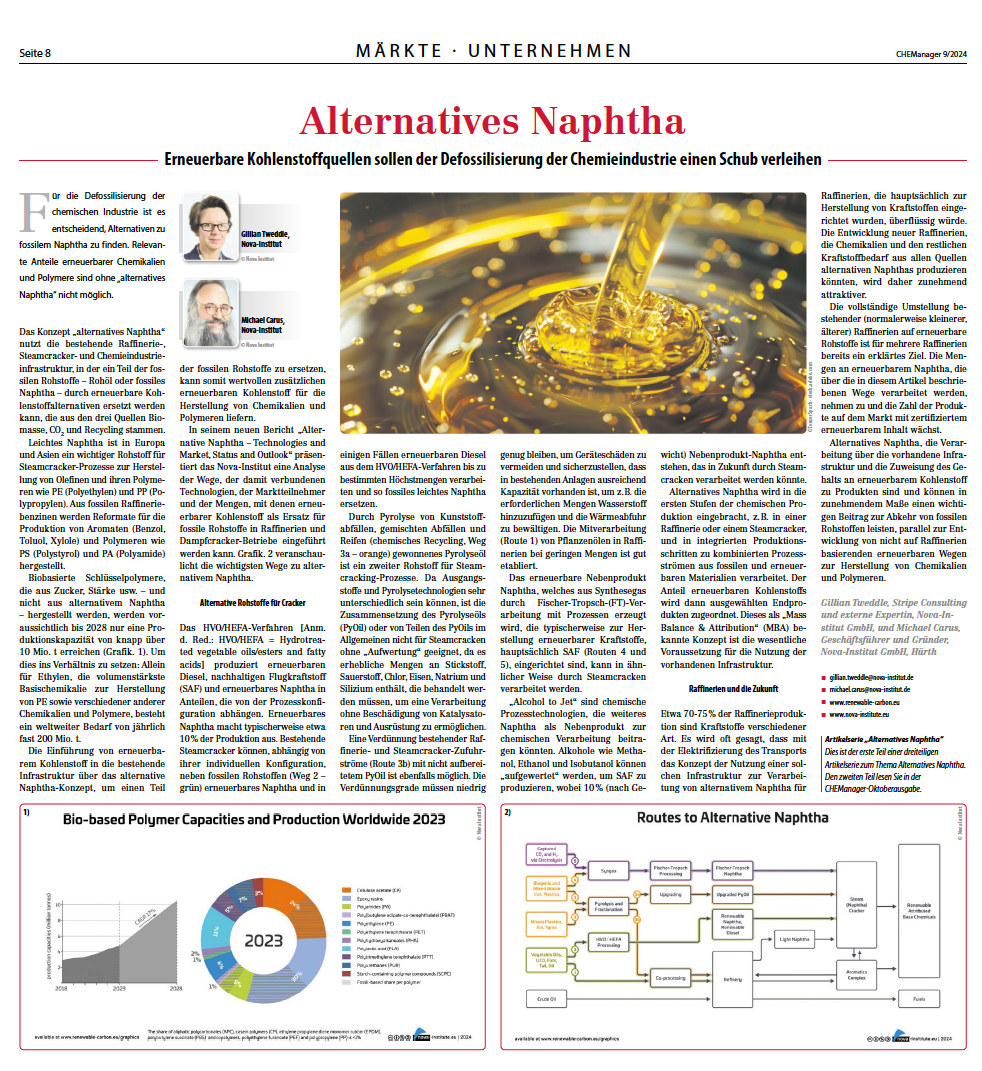
Alternatives Naphtha – Erneuerbare Kohlenstoffquellen sollen der Defossilisierung der Chemieindustrie einen Schub verleihen (Gastbeitrag Teil 1) (PDF)
Markets & Economy, Technology
1 Page
61 Downloads 61 Downloads
2024-09
FREE
61
DownloadsFür die Defossilisierung der chemischen Industrie ist es entscheidend, Alternativen zu fossilem Naphtha zu finden. Relevante Anteile erneuerbarer Chemikalien und Polymere sind ohne „alternatives Naphtha“ nicht möglich.
Das Konzept „alternatives Naphtha“ nutzt die bestehende Raffinerie-, Steamcracker- und Chemieindustrieinfrastruktur, in der ein Teil der fossilen Rohstoffe – Rohöl oder fossiles Naphtha – durch erneuerbare Kohlenstoffalternativen ersetzt werden kann, die aus den drei Quellen Biomasse, CO2 und Recycling stammen.
Dieser Artikel ist im Rahmen einer Serie von Gastbeiträgen im CHEManager erschienen. Es handelt sich um „Alternatives Naphtha Teil 1“ – aus CHEManager 09/2024.
Hier finden sie den Artikel auch bei CHEManager.
-
Chemical and Physical Recycling – RCI Position Paper (May 2024)
Policy, Technology
4 Pages
1014 Downloads 1014 Downloads
2024-05
FREE
Free Shipping1014
DownloadsIn this position paper, the RCI describes that chemical and physical recycling play essential roles in realising the objectives of the Green Deal and advancing the circular economy. These technologies are indispensable for the green transition.
This position paper identifies eleven requirements to create secure demand, drive investment and further improve the technology field. These include general acceptance of the technology; mandatory recycled content for all polymers/plastics in all applications; recognition and clarification of rules for the calculation of recycling rates; full acceptance of mass balance & attribution with fuel-use excluded; accelerated approval of new chemical and physical recycling facilities; expansion of recycling infrastructure for all sectors beyond packaging; and the extension of CO2 pricing for waste incineration in the ETS combined with a landfill ban.
Additionally, RCI advocates for a pragmatic approach, emphasising that while closed-loop recycling is a noble goal for sectors such as packaging, textiles and automobiles, it should not be approached too dogmatically. Flexibility is essential to prevent environmental and economic inefficiencies. If the waste stream of one sector can be better used in another, this should be possible.
-
Bio-based Building Blocks and Polymers – Global Capacities, Production and Trends 2023–2028 – Short Version (PDF)
Markets & Economy
28 Pages
2488 Downloads 2488 Downloads
2024-03
FREE
2488
DownloadsNew report released on the global bio‑based polymer market 2023 – a deep and comprehensive insight into a dynamically growing market
The year 2023 was a promising year for bio‑based polymers: PLA capacities have been increased by almost 50 %, and at the same time polyamide capacities are steadily increasing, as well as epoxy resin production. Capacities for 100 % bio-based PE have been expanded and PE and PP made from bio‑based naphtha are being further established with growing volumes. Current and future expansions for PHAs are still on the horizon. After hinting at a comeback in 2022 bio-based PET production dropped in 2023 by 50 %.
DOI No.: https://doi.org/10.52548/VXTH2416
-
Bio-based Building Blocks and Polymers – Global Capacities, Production and Trends 2023–2028 (PDF)
Markets & Economy
438 Pages
2024-03
1,000 € – 3,000 €Price range: 1,000 € through 3,000 € ex. tax
Plus 19% MwSt.Select
licenceNew report released on the global bio‑based polymer market 2023 – a deep and comprehensive insight into a dynamically growing market
The year 2023 was a promising year for bio‑based polymers: PLA capacities have been increased by almost 50 %, and at the same time polyamide capacities are steadily increasing, as well as epoxy resin production. Capacities for 100 % bio-based PE have been expanded and PE and PP made from bio‑based naphtha are being further established with growing volumes. Current and future expansions for PHAs are still on the horizon. After hinting at a comeback in 2022 bio-based PET production dropped in 2023 by 50 %.
DOI No.: https://doi.org/10.52548/VXTH2416
-
Making a Case for Carbon Capture and Utilisation (CCU): It Is Much More than Just a Carbon Removal Technology” – RCI Report (July 2023)
Markets & Economy, Policy, Sustainability & Health, Technology
48 Pages
2168 Downloads 2168 Downloads
2023-07
FREE
Free Shipping2168
DownloadsThis scientific background paper highlights the importance of Carbon Capture and Utilisation (CCU) and the need for more political recoginition and support for CCU.
CCU enables the substitution of fossil carbon in sectors where carbon is necessary, supports the full defossilisation of the chemical and derived material industries, creates a circular economy, reduces the emission gap, promotes sustainable carbon cycles, fosters innovation, generates local value and stimulates job growth.
CCU is much more than a carbon removal technology: the technology offers multiple solutions to pressing problems of our modern world and can support several Sustainable Development Goals if implemented properly.
In total, 14 different benefits and advantages of CCU are described and discussed in the paper. A key advantage is that CCU supplies renewable carbon to – and thereby substitutes fossil carbon in – sectors that will require carbon in the long run. This includes the chemical sectors and products like polymers, plastics, solvents, paints, detergents, cosmetics or pharmaceuticals. But CCU is also essential to a long-term net-zero strategy, crucial for creating a sustainable circular economy, providing solutions for scaling up the renewable energy system, and bringing multiple benefits for innovation and business.
The relevance of the technology is not yet accepted in Europe, but the RCI wants to make a very clear statement: CCU is a central pillar for the biggest transformation of the chemical and material industry since the industrial revolution.
DOI No.: https://doi.org/10.52548/VYKR3129
-
Commission Proposal for a Packaging and Packaging Waste Regulation – RCI Position Paper (May 2023)
Policy
3 Pages
296 Downloads 296 Downloads
2023-05
FREE
296
DownloadsThis position paper highlights chances for the EU to lead the way to a sustainable packaging industry and to promote innovation
In November 2022, the Commission adopted the Proposal for a Regulation of the European Parliament and of the Council on packaging and packaging waste, amending Regulation (EU) 2019/1020 and Directive (EU) 2019/904, and repealing Directive 94/62/EC. The proposed regulation includes several rules that would – if implemented – push for a much stronger circular economy in the packaging sector, due to higher re-use and refill quotas, higher use of recycled materials and mandatory composting of certain hard-to-recycle products.
The Renewable Carbon Initiative (RCI) welcomes this proposal and wants to offer several suggestions to strengthen it further and get implementation closer to the market realities of Europe.
1. Set ambitious targets for all types of renewable content:
A complementary renewable content target should be added to the proposal promoting the use of bio- and CO2-based feedstocks in packaging similar to recycling.2. Keep Article 8 as it is – scientific evidence shows that these products offer true environmental benefits from being compostable
The proposal, following scientific evidence, requires that certain types of tea and coffee packaging, sticky labels attached to fruit and vegetables as well as very lightweight plastic carrier bags shall be compostable in industrially controlled conditions in bio-waste treatment facilities.3. Support the market uptake of all state-of-the-art recycling technologies
To actually achieve the ambitious recycling quotas and recycled content targets, technologies will have to evolve. Advanced recycling technologies (i.e. depolymerisation) are key. -
Carbon Dioxide (CO₂) as Feedstock for Chemicals, Advanced Fuels, Polymers, Proteins and Minerals – Short Version (PDF)
Markets & Economy, Technology
18 Pages
1050 Downloads 1050 Downloads
2023-04
FREE
1050
DownloadsNew report on the use of CO₂ for chemicals, advanced fuels, polymers, proteins and minerals by nova-Institute – A deep and comprehensive insight into the evolving technologies, trends and the dynamically growing market of CO₂ transformation and utilisation.
Several successfully implemented technologies are now in commercial use, and many more are at the laboratory and pilot stage. A current total production capacity of novel CO₂-based products of about 1.3 Mt/a in 2022 is observed. The production capacity in 2022 is dominated by the production of CO₂-based aromatic polycarbonates, ethanol from captured CO/CO₂, aliphatic polycarbonate and methanol. By 2030, the capacity outlook for CO₂-based products is expected to exceed 6 Mt/a of CO₂-based products. High dynamic growth is observed for methanol projects, methane plants, ethanol and hydrocarbons – the latter especially for the aviation sector. The potential of CCU has been recognised by several global brands which are already expanding their feedstock portfolio. However, in Europe, investments and prospects for CO₂ utilisation are largely undermined by a lack of political support. In contrast, we see supportive policies in China as well as in the US with the Inflation Reduction Act. Such smart policies are needed to bridge the gap between now and 2050 for companies to remain competitive in the sustainable transformation.nova-Institute’s new report examines this renewable carbon source in detail: Which products can be made from CO₂, and by which processes? To which extend have the technologies already been developed and implemented in pilot, demonstration and commercial plants? Which companies are working on technologies to uses CO₂ as a feedstock? What are the trends in CO₂ utilisation in the coming years?
This report addresses the fuel, chemical and materials industries, brands, technology scouts, investors, and policy makers. The report provides 240 pages of information on CO₂ utilisation. All the 116 companies mentioned are described in detailed profiles.
-
Carbon Dioxide (CO₂) as Feedstock for Chemicals, Advanced Fuels, Polymers, Proteins and Minerals (PDF)
Markets & Economy, Technology
242 Pages
2023-04
2,500 € – 10,000 €Price range: 2,500 € through 10,000 € ex. tax
Plus 19% MwSt.Press
release Select
licenceNew report on the use of CO₂ for chemicals, advanced fuels, polymers, proteins and minerals by nova-Institute – A deep and comprehensive insight into the evolving technologies, trends and the dynamically growing market of CO₂ transformation and utilisation.
Several successfully implemented technologies are now in commercial use, and many more are at the laboratory and pilot stage. A current total production capacity of novel CO₂-based products of about 1.3 Mt/a in 2022 is observed. The production capacity in 2022 is dominated by the production of CO₂-based aromatic polycarbonates, ethanol from captured CO/CO₂, aliphatic polycarbonate and methanol. By 2030, the capacity outlook for CO₂-based products is expected to exceed 6 Mt/a of CO₂-based products. High dynamic growth is observed for methanol projects, methane plants, ethanol and hydrocarbons – the latter especially for the aviation sector. The potential of CCU has been recognised by several global brands which are already expanding their feedstock portfolio. However, in Europe, investments and prospects for CO₂ utilisation are largely undermined by a lack of political support. In contrast, we see supportive policies in China as well as in the US with the Inflation Reduction Act. Such smart policies are needed to bridge the gap between now and 2050 for companies to remain competitive in the sustainable transformation.nova-Institute’s new report examines this renewable carbon source in detail: Which products can be made from CO₂, and by which processes? To which extend have the technologies already been developed and implemented in pilot, demonstration and commercial plants? Which companies are working on technologies to uses CO₂ as a feedstock? What are the trends in CO₂ utilisation in the coming years?
This report addresses the fuel, chemical and materials industries, brands, technology scouts, investors, and policy makers. The report provides 240 pages of information on CO₂ utilisation. All the 116 companies mentioned are described in detailed profiles.
DOI No.: https://doi.org/10.52548/HKBS8158
-
nova-Session: “Bio- and CO₂-based Polymers: Production, Trends 2022-2027 and the latest Policy Developments” (Proceedings, PDF)
Markets & Economy, Policy, Sustainability & Health, Technology
2023-03
50 € ex. tax
Plus 19% MwSt.Add to
cartThe download of the proceedings contains all six presentations of the nova-Session (March 2023).
Bio-based and CO2-based Solutions – Where are we heading?
The only way for chemicals and plastics to become sustainable, climate-friendly and part of the circular economy is the complete substitution of fossil carbon with renewable carbon from alternative sources: biomass, CO2 and recycling. We see strong investment in all three sectors, with growth rates far exceeding that of fossil polymers – i.e. fossil polymers are being substituted in the market.
The session will focus on developments in bio- and CO2-based polymers and building blocks: Bio-based polymers are estimated to grow at a CAGR of 14 % from 2022 to 2027. Some examples: Bio-based epoxy resin production is on the rise, PTT regained attractiveness after several years of constant capacities and PE and PP made from bio based naphtha are being further established with growing volumes. Increased capacities for PLA are ongoing, after being sold out in 2019. Current and future expansions for bio based polyamides as well as PHAs are on the horizon. And also, bio-based PET is getting back in the game.
Additionally, the use of CO2 as chemical feedstock for building blocks and polymers has been intensively diversified. Several successfully implemented technologies used at commercial level are in place and many more at the laboratory and pilot phase. Besides the long-established use of CO2 for the synthesis of polycarbonates, also polyurethanes are based on it. The most notable biotechnological conversion pathway of a syngas produces ethanol at commercial scale. Additionally, high interest is also observed in CO2-based methanol and in CO2-based hydrocarbons, which can be used for fuel, chemical and polymers applications. A current total production capacity of these CO2-based products of ca. 1.3 Mt/a in 2022 is observed and a strong increase in capacity is expected by 2027.
The EU policy landscape has seen significant updates in the final weeks of 2022 with the proposed Packaging and Packaging Waste Regulation and the publication of the Policy Framework on bio-based, biodegradable and compostable plastics. How these updates may affect CO2 and bio-based polymers will be addressed in the session.