Showing 81–100 of 536
-
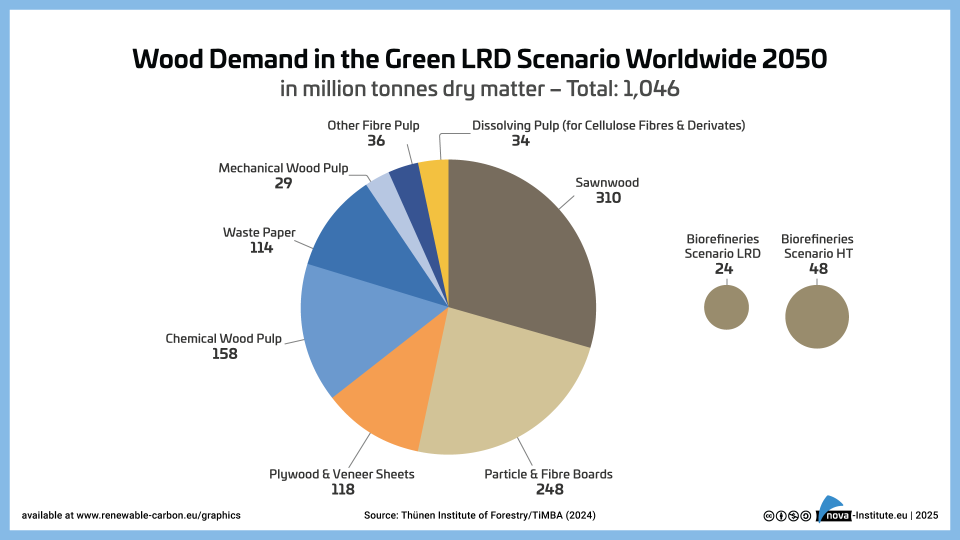
Wood Demand in the Green LRD Scenario Worldwide 2050 – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
17 Downloads
17 Downloads
2025-02
FREE
17
Downloads -
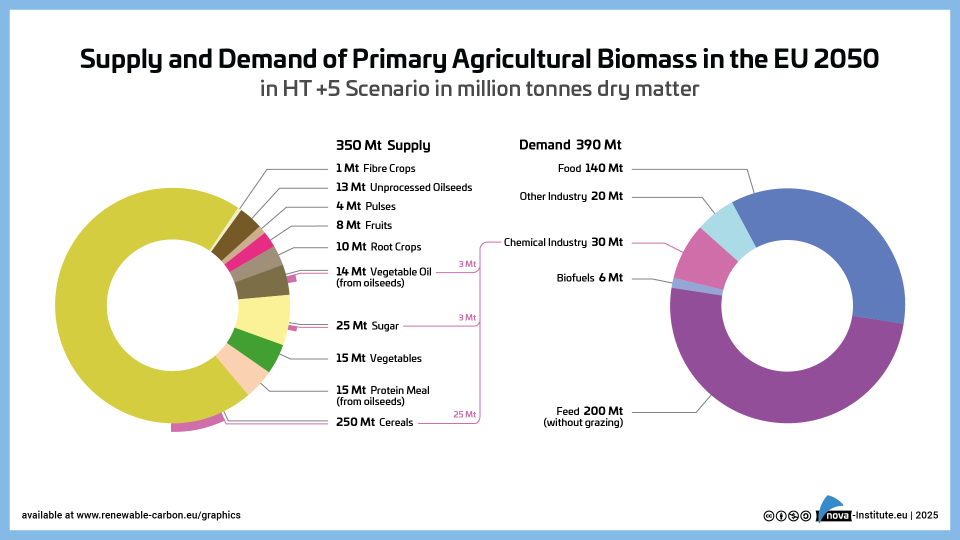
Supply and Demand of Agricultural Biomass in the EU 2050 in HT +5 Scenario – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
33 Downloads
33 Downloads
2025-02
FREE
33
Downloads -
Is there Enough Biomass to Defossilise the Chemicals and Derived Materials Sector by 2050? – A Joint BIC and RCI Scientific Background Report (PDF)
Markets & Economy, Policy, Sustainability & Health
41 Pages
2149 Downloads
2149 Downloads
2025-02
FREE
Free Shipping2149
DownloadsThis reports presents the findings of a joint project of the Bio-based Industries Consortium (BIC) and the Renewable Carbon Initiative (RCI), which focuses on whether agricultural and woody biomass combined sustainably provide enough biomass to meet 20% of the future carbon demand of the chemical and derived materials industries in 2050 (up from 5.5% (EU27) and 10% (global) in 2023).
This leading question was investigated with professional experts to model a business-as-usual, a low resource depletion, and a high-tech scenario to better analyse the possible ranges of biomass availability under different developments.
Agriculture: By 2050, under the BAU scenario, production is projected to increase by 31% to 5.07 billion tonnes. Cereals increase by 32% to 3.1 billion tonnes, sugar by 40% to 340 million tonnes and vegetable oils by 45% to 317 million tonnes. In the Green LRD scenarios, production is projected to increase by 24–26%, and in the Green HT scenarios by 38–53% – compared to 31% in the BAU scenario.
Forestry: Global supply and demand of industrial roundwood (coniferous and non-coniferous) will increase by an estimated 38% between 2020 and 2050, from 0.9 to 1.3 billion tdm. The largest increase in supply is expected in Asia (69%), including China and Russia, but a significant increase of 32% is also seen for Europe.
The report concludes that sustainably meeting 20% of total carbon demand of the chemicals and derived materials sector in 2050 via biomass seems a realistic and achievable estimate.
DOI No.: https://doi.org/10.52548/PIRL6916
-
EU and Global: Biomass Demand for Transport Fuels, Aviation and Shipping up to 2050 and Implications for Biomass Supply to the Chemical Sector – RCI Report (January 2025)
Markets & Economy, Policy, Sustainability & Health
44 Pages
1379 Downloads
1379 Downloads
2025-01
FREE
Free Shipping1379
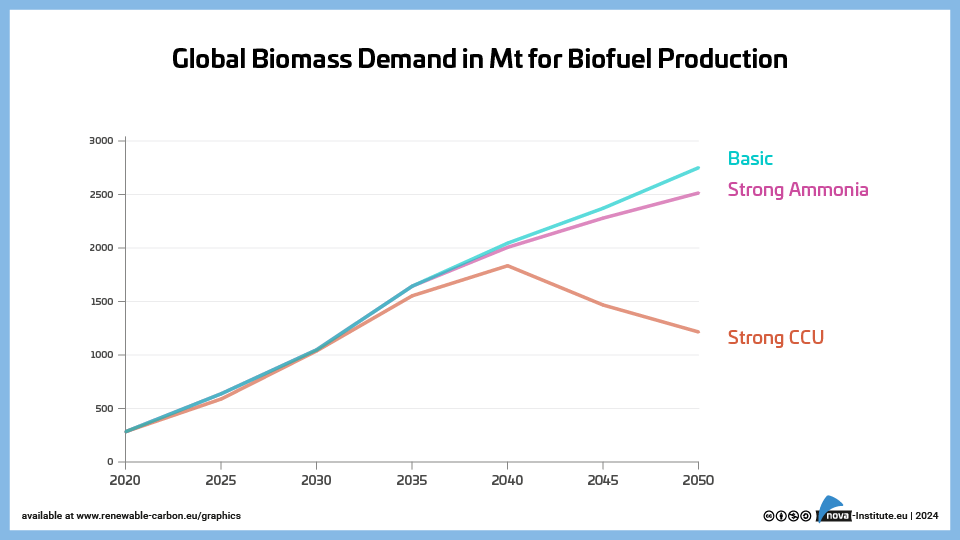
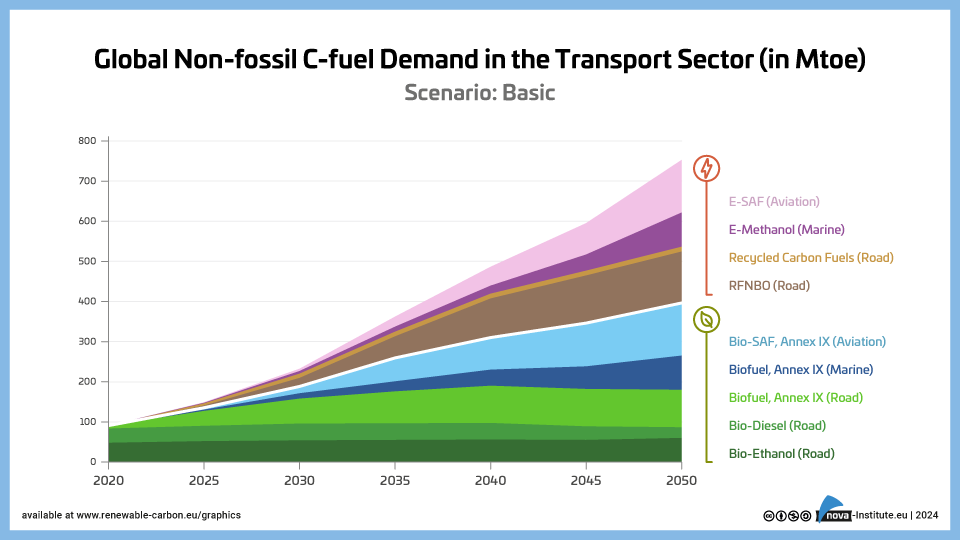
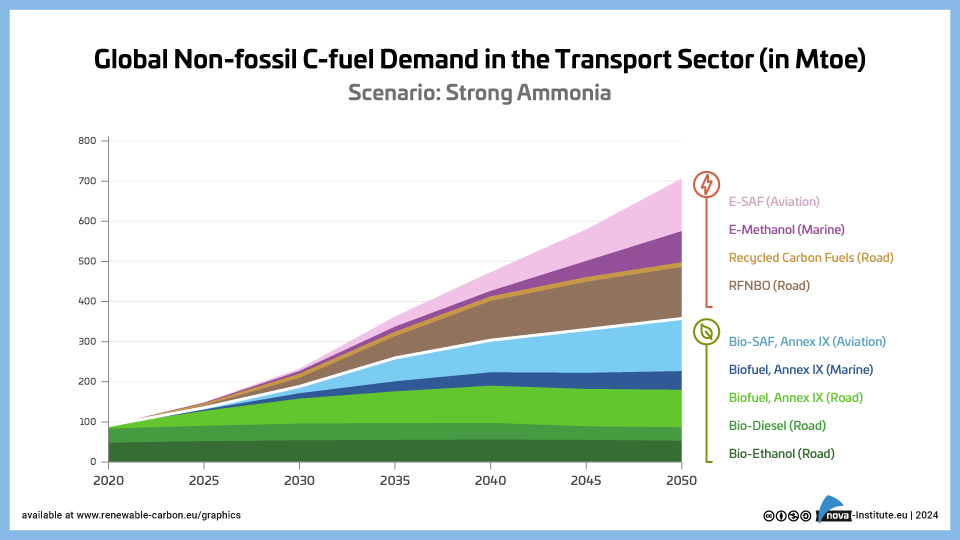
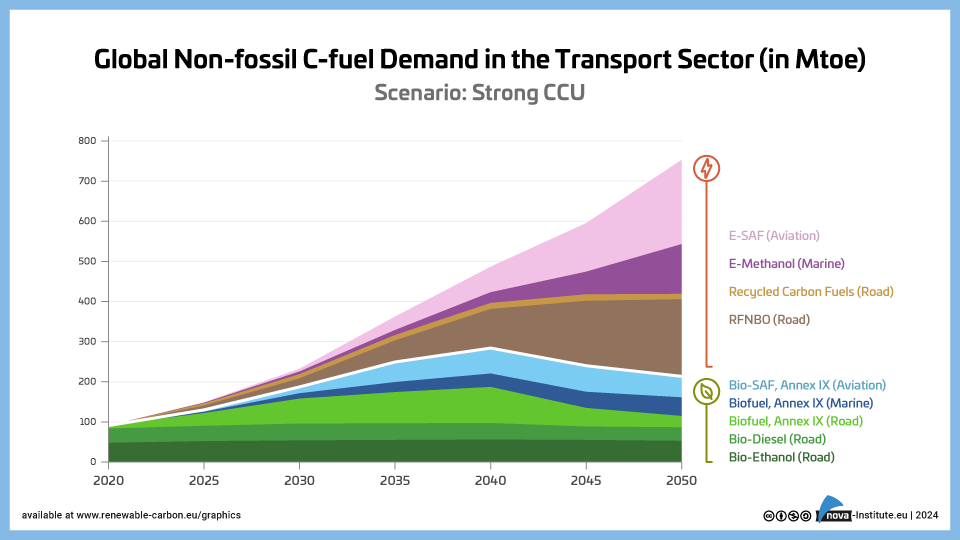
DownloadsThe Renewable Carbon Initiative’s Scientific Background Report explores three potential future scenarios for carbon-based fuel demand up to 2050 under current policy frameworks. It predicts a sharp rise in the demand for second-generation biomass biofuels, driven primarily by increasing quotas for aviation and shipping fuels. This growth raises concerns about ecological and resource sustainability and creates challenges for sectors like chemicals and materials, which rely on renewable carbon to reduce fossil dependency. Without similar regulatory incentives, these sectors may face limited access to critical feedstocks like biomass and captured carbon.
The report highlights that while bio-based and synthetic fuel production could indirectly benefit the chemical industry through by-products, competition with the fuel sector poses significant obstacles.The report includes 11 tables, 9 graphics, and a detailed overview of EU fuel regulations. Though focused on Europe, it also provides global insights, making it a valuable resource for stakeholders in biomass and CO2 utilisation sectors.
-
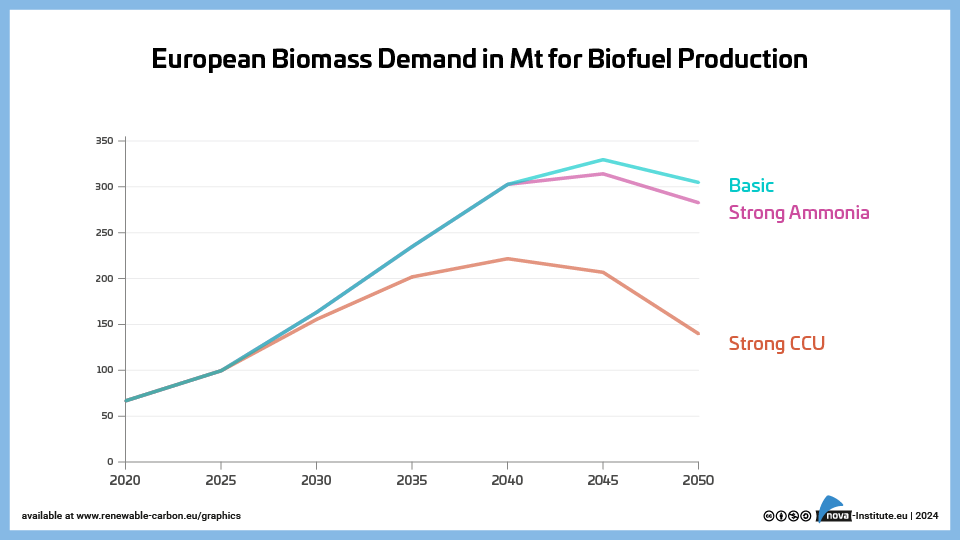
European Biomass Demand in Mt for Biofuel Production – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
34 Downloads
34 Downloads
2025-01
FREE
34
Downloads -
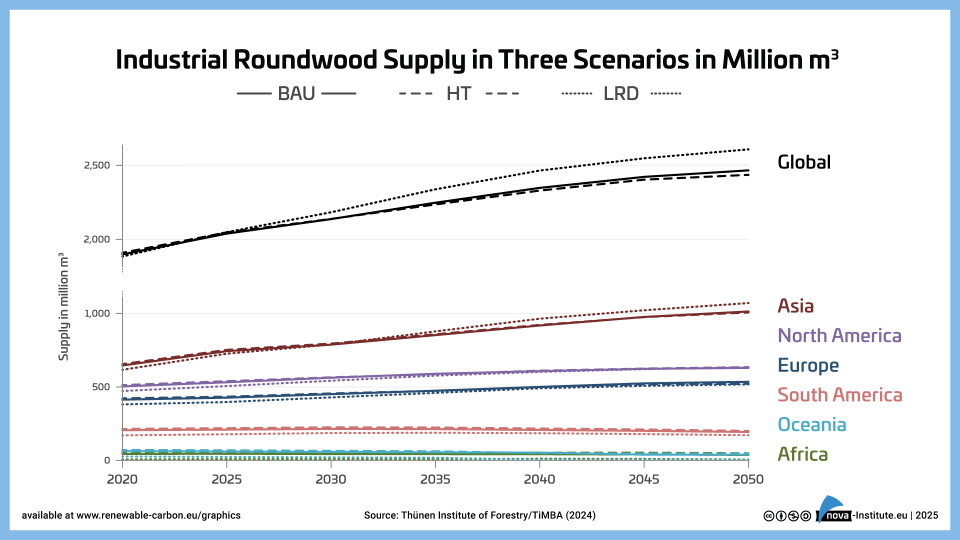
Industrial Roundwood Production in Three Scenarios in Million m3 – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
9 Downloads
9 Downloads
2025-01
FREE
9
Downloads -
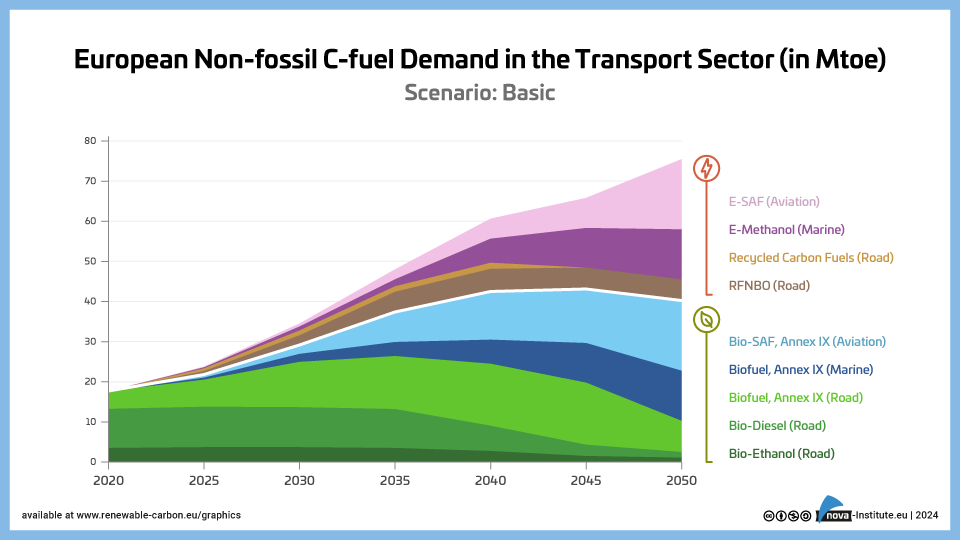
European Non-fossil C-fuel Demand in the Transport Sector – Basic – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
33 Downloads
33 Downloads
2025-01
FREE
33
Downloads -
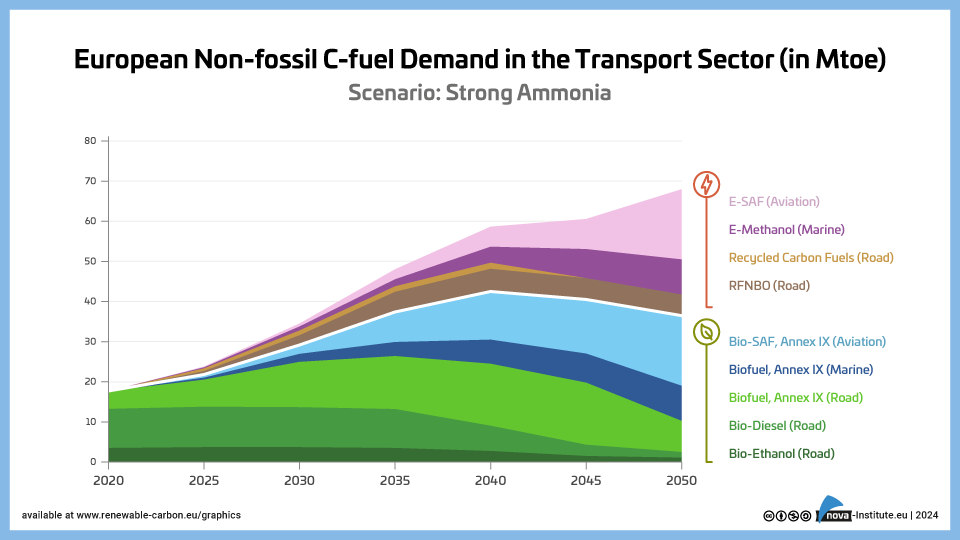
European Non-fossil C-fuel Demand in the Transport Sector – Strong Ammonia – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
12 Downloads
12 Downloads
2025-01
FREE
12
Downloads -
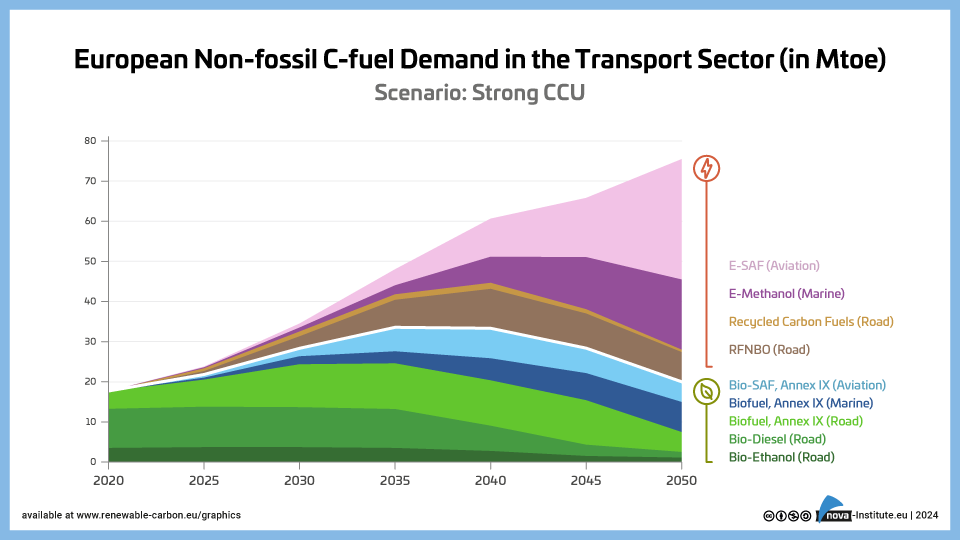
European Non-fossil C-fuel Demand in the Transport Sector – Strong CCU – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
24 Downloads
24 Downloads
2025-01
FREE
24
Downloads -
Global Biomass Demand in Mt for Biofuel Production – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
29 Downloads
29 Downloads
2025-01
FREE
29
Downloads -
Global Non-fossil C-fuel Demand in the Transport Sector – Basic – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
31 Downloads
31 Downloads
2025-01
FREE
31
Downloads -
Global Non-fossil C-fuel Demand in the Transport Sector – Strong Ammonia – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
16 Downloads
16 Downloads
2025-01
FREE
16
Downloads -
Global Non-fossil C-fuel Demand in the Transport Sector – Strong CCU – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
661 Downloads
661 Downloads
2025-01
FREE
661
Downloads -
Advanced Recycling Conference 2024 (Proceedings)
Markets & Economy, Policy, Sustainability & Health, Technology
2024-12
50 € ex. tax
Plus 19% MwSt.Press
release Add to
cartThe proceedings of the Advanced Recycling Conference 2024 (20-21 November, https://advanced-recycling.eu) contain 42 conference presentations, the conference journal, sponsor documents and the press release.
-
Evaluation of Recent Reports on the Future of a Net-Zero Chemical Industry in 2050 – RCI Report (November 2024)
Markets & Economy, Policy, Sustainability & Health
20 Pages
2055 Downloads
2055 Downloads
2024-11
FREE
Free Shipping2055
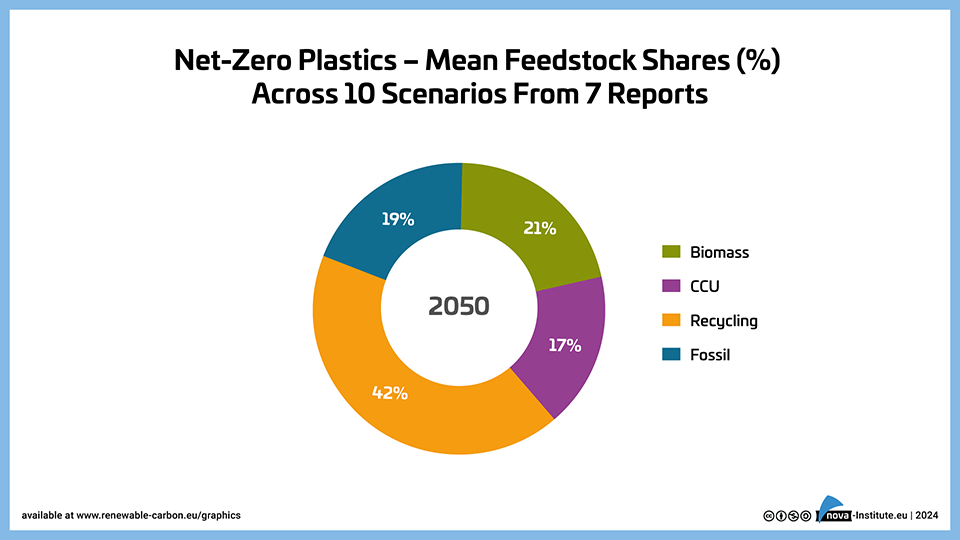
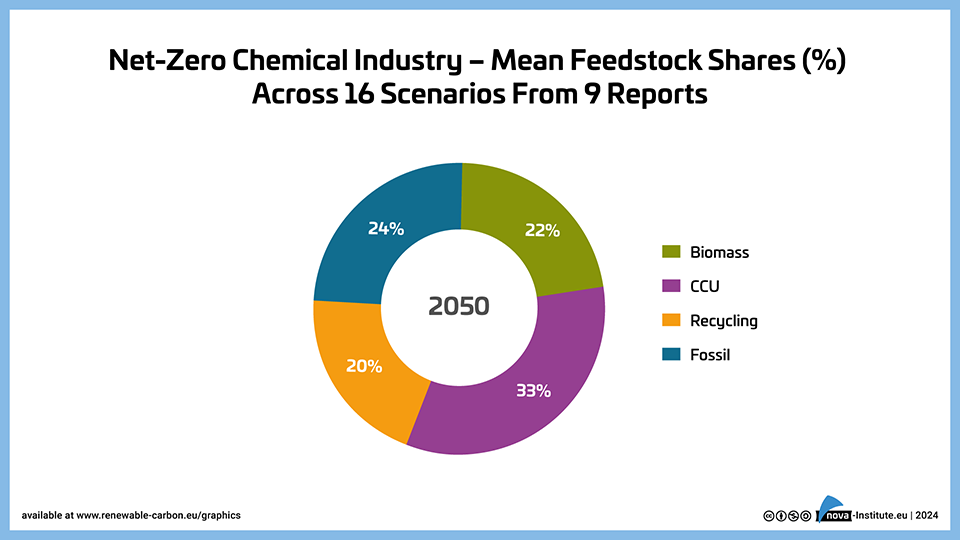
DownloadsThe Renewable Carbon Initiative’s Scientific Background Report assesses 24 scenarios from 15 studies to envision a net-zero chemical industry by 2050. The analysis anticipates continued growth in chemical production, projecting a 2.4-fold increase in global feedstock demand by 2050 compared to 2020 levels, with most expansion expected outside Europe while European feedstock volumes remain stable. To achieve net-zero emissions, the industry is projected to undergo a significant shift in feedstocks, with key renewable carbon sources identified as biomass (22%), carbon capture and utilisation (33%), and recycling (20%), while the remaining 24% comes from fossil sources with carbon capture and storage. For plastics specifically, recycling is expected to play an even larger role, accounting for 42% of feedstocks on average. This transition will require continued innovation and investment in renewable carbon technologies to meet ambitious defossilisation goals.
The report provides invaluable insights for industry leaders, policymakers, and researchers, highlighting the urgent need for action to achieve a net-zero future in the chemical sector by 2050.
DOI No.: https://doi.org/10.52548/SXWV6083
-
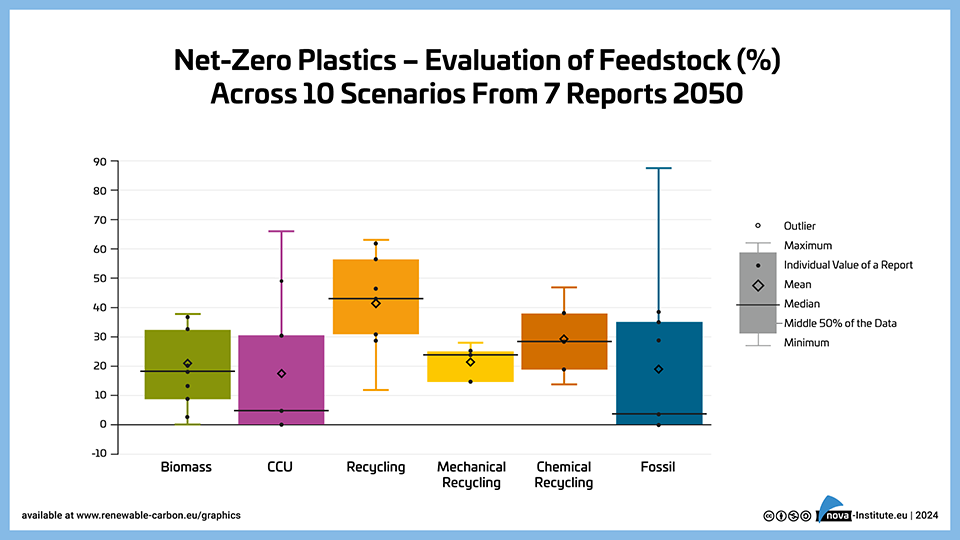
Net-Zero Plastics – Evaluation of Feedstock (%) Across 10 Scenarios from 7 Reports 2050 – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
137 Downloads
137 Downloads
2024-11
FREE
137
DownloadsThe graph illustrates feedstock projections specifically for the plastics sector by 2050, analysing 10 scenarios from 7 reports, where recycling emerges as the dominant feedstock at 42% (combining mechanical and chemical recycling), while biomass (21%), CCU (17%), and fossil with CCS (19%) play supporting roles. The data shows less variation in projections compared to the chemical industry overall, suggesting stronger agreement on the future role of recycling in plastics production.
-
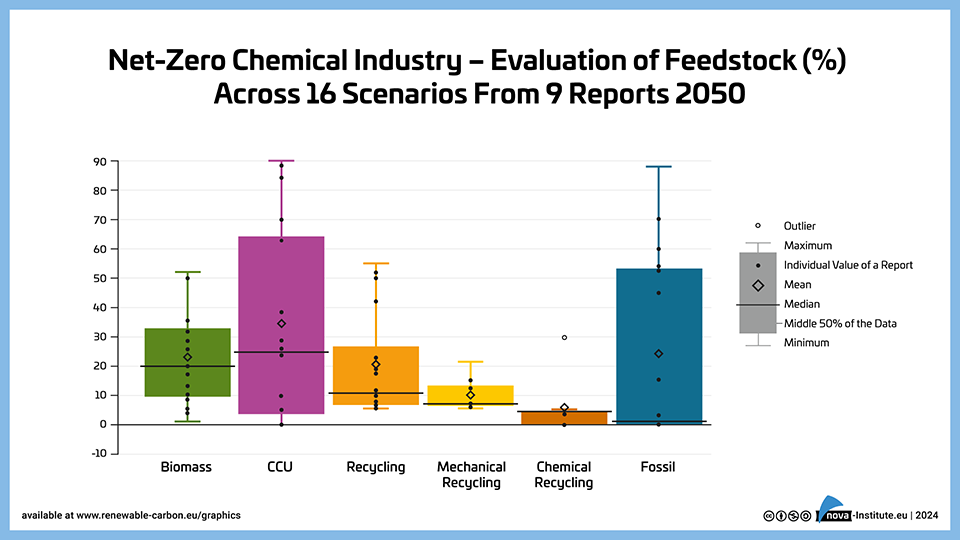
Net-Zero Chemical Industry – Evaluation of Feedstock (%) Across 16 Scenarios from 9 Reports 2050 – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
117 Downloads
117 Downloads
2024-11
FREE
117
DownloadsThe graph shows the distribution of feedstock sources for the net-zero chemical industry by 2050, based on 16 scenarios from 9 reports, with CCU having the highest mean share at 33%, followed by biomass (22%), recycling (20%, split between mechanical and chemical), and fossil with CCS (24%). The data reveals significant variability across scenarios, particularly for CCU which ranges from near 0% to 90%, while both biomass and recycling show more moderate ranges, indicating a general consensus on their roles in the future chemical industry.
-
Net-Zero Plastics – Mean Feedstock Shares (%) Across 10 Scenarios From 7 Reports – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
102 Downloads
102 Downloads
2024-11
FREE
102
DownloadsThe graph presents the mean feedstock shares for the 2050 net-zero plastics sector, derived from 10 scenarios across 7 reports. In this projection, recycling dominates with a 42% share, followed by biomass (21%), fossil & CCS (19%), and CCU (17%), highlighting the increased potential for circularity in the plastics industry compared to the broader chemical sector.
-
Net-Zero Chemical Industry – Mean Feedstock Shares (%) Across 16 Scenarios From 9 Reports – Graphic (PNG)
Markets & Economy, Policy, Sustainability & Health
1 Page
77 Downloads
77 Downloads
2024-11
FREE
77
DownloadsThe graph illustrates the mean feedstock shares projected for the 2050 net-zero chemical industry, based on 16 scenarios across 9 reports. The chart shows a diverse mix of feedstocks, with CCU (33%) and recycling (20%) playing significant roles alongside biomass (22%), while fossil & CCS still account for 24% of the feedstock share.
-
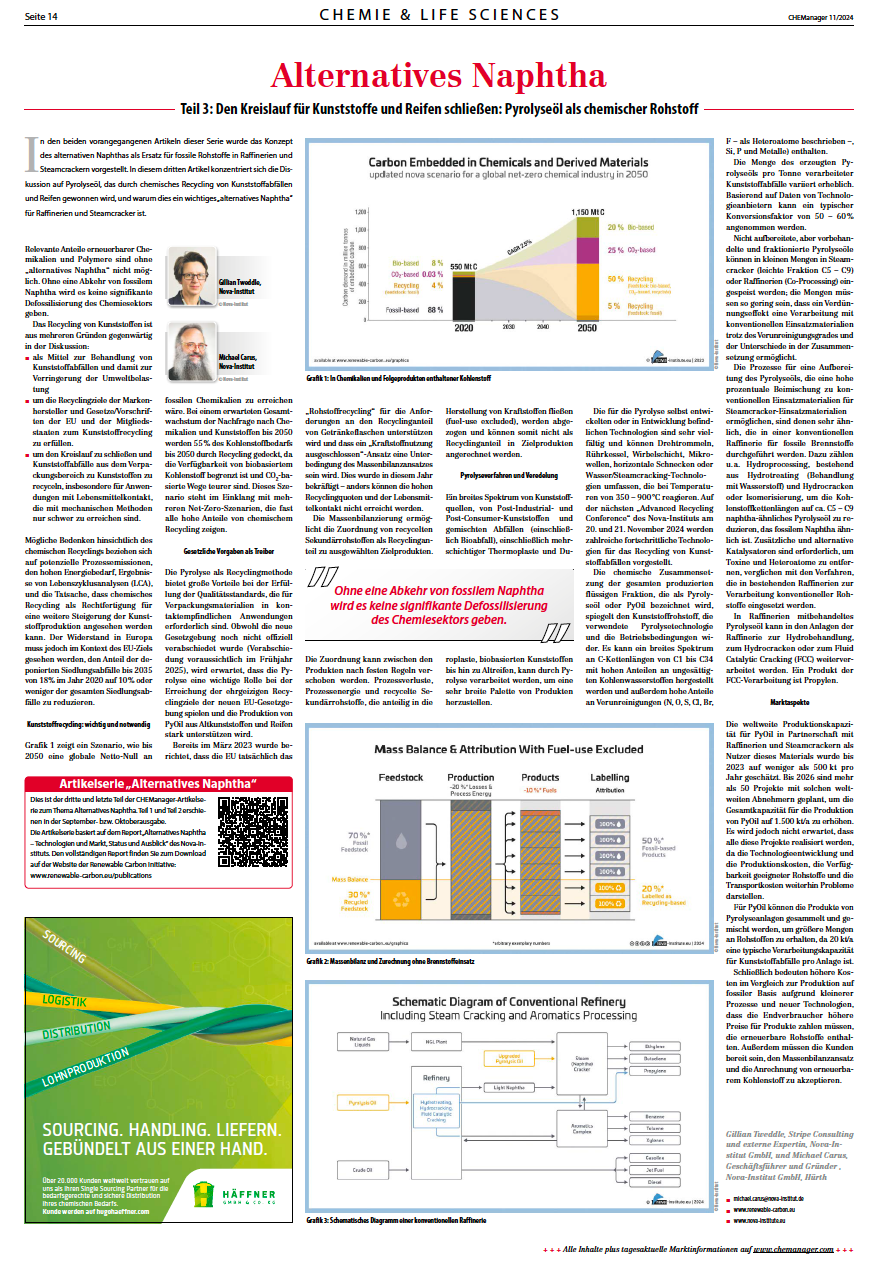
Alternatives Naphtha – Den Kreislauf für Kunststoffe und Reifen schließen: Pyrolyseöl als chemischer Rohstoff (Gastbeitrag Teil 3) (PDF)
Markets & Economy, Technology
1 Page
118 Downloads
118 Downloads
2024-11
FREE
118
DownloadsIn den beiden vorangegangenen Artikeln dieser Serie wurde das Konzept des alternativen Naphthas als Ersatz für fossile Rohstoffe in Raffinerien und Steamcrackern vorgestellt. In diesem dritten Artikel konzentriert sich die Diskussion auf Pyrolyseöl, das durch chemisches Recycling von Kunststoffabfällen und Reifen gewonnen wird, und warum dies ein wichtiges „alternatives Naphtha“ für Raffinerien und Steamcracker ist.
Relevante Anteile erneuerbarer Chemikalien und Polymere sind ohne „alternatives Naphtha“ nicht möglich. Ohne eine Abkehr von fossilem Naphtha wird es keine signifikante Defossilisierung des Chemiesektors geben.
Dieser Artikel ist im Rahmen einer Serie von Gastbeiträgen im CHEManager erschienen. Es handelt sich um „Alternatives Naphtha Teil 3“ – aus CHEManager 11/2024.
Hier finden sie den Artikel auch bei CHEManager.